


Key Takeaways
- Shares of Manchester United traded down approximately 4% on Wednesday to around $19.60.
- The club’s quarterly deficit expanded significantly to £28.7 million.
- Quarterly revenue declined 4% to £157.5 million, with adjusted EBITDA falling 22.9%.
- Annual revenue hit an all-time high of £677.6 million.
- Market participants are evaluating the club’s debt obligations and capital requirements for a proposed 100,000-capacity stadium.
Manchester United (MANU) shares declined approximately 4% on Wednesday, trading near $19.60 following the release of its fiscal fourth-quarter financial results that presented a mixed picture. The stock had settled at $20.51 on Tuesday, making the earnings announcement the most obvious driver behind Wednesday’s selloff.
Revenue for the quarter decreased 4% compared to the prior year, falling to £157.5 million from £164.1 million. Adjusted EBITDA saw a steeper decline of 22.9%, dropping to £28.9 million from £37.5 million.
The deficit ballooned considerably more dramatically, expanding to £28.7 million versus £3.9 million in the comparable period last year. The club recorded an adjusted deficit of £28.2 million for the three-month period.
Commercial Operations Drive Quarterly Weakness
Commercial income contracted 18.1% to £72.2 million, while sponsorship-related revenue plummeted 26.2%. The comparison period a year ago included benefits from a post-season promotional tour across Malaysia and Hong Kong, which wasn’t replicated this year due to FIFA World Cup scheduling.

Matchday income also retreated 4.3% to £35.6 million. The broadcasting segment provided a bright spot, surging 28.4% to £49.7 million as the men’s squad delivered enhanced Premier League results.
The disappointing quarter stands in sharp contrast to a robust full fiscal year performance. Manchester United achieved record-breaking revenue of £677.6 million, representing a 1.7% increase, even without participation in UEFA competitions.
Full-year adjusted EBITDA climbed to an all-time high of £216.4 million, up 18.4%. Operating profit swung to £22.6 million from a £18.4 million deficit as cost-cutting initiatives and enhanced Premier League standings supported financial results.
The men’s squad secured third place in the Premier League standings and has qualified for Champions League participation in the 2026/27 campaign. This qualification should generate incremental broadcasting and matchday income relative to the previous season.
Stadium Development Plans Add Investment Uncertainty
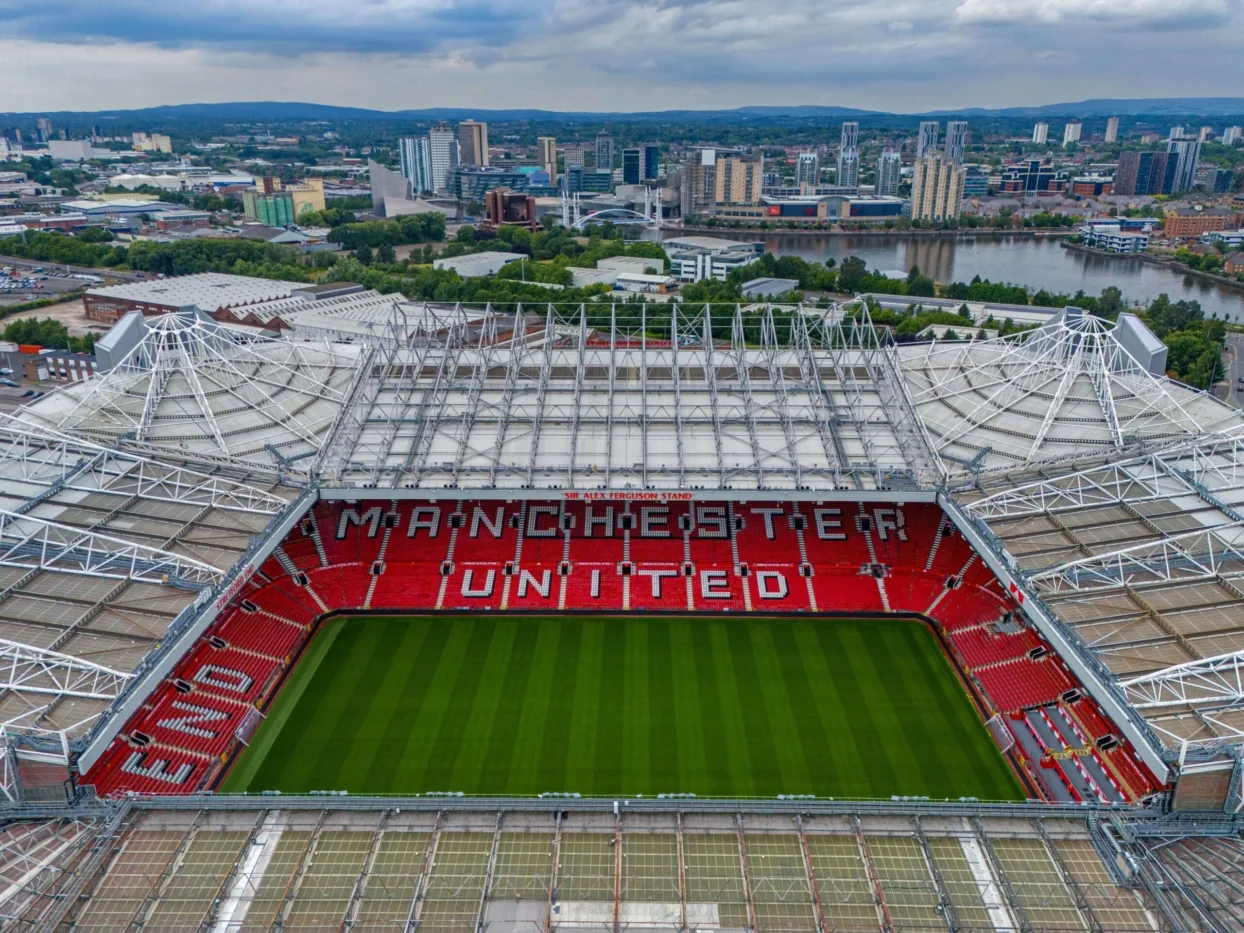
Market observers are closely monitoring the club’s ambitious plans for a 100,000-capacity stadium. Manchester United has secured most of the necessary land parcels for this development, including a 25-acre plot adjacent to Old Trafford.
The football club allocated £63.5 million during fiscal 2026 toward land acquisitions tied to the stadium initiative. Overall property and equipment capital expenditures totaled £85.9 million for the fiscal year.
Debt levels represent an additional concern for shareholders. Non-current borrowings stood at $775 million as of June 30, up from $650 million twelve months prior, while the revolving credit facility carried £110 million in outstanding balances.
The organization closed the fiscal period with £67.2 million in cash and cash equivalents, down from £86.1 million. Elevated financing expenses, player acquisitions, and forthcoming stadium construction costs are likely to remain significant considerations for the investment community.
Management has projected fiscal 2027 revenue in the range of £740 million to £760 million, with adjusted EBITDA forecasted between £205 million and £225 million. This guidance incorporates the financial impact of Champions League participation but leaves execution capabilities, on-field performance, and financing arrangements as material risk factors.
The most recent confirmed financial data reveals a challenging fourth quarter offset by record-setting annual revenue and EBITDA figures. Wednesday’s share price decline indicates market participants are placing greater emphasis on the quarterly deficit, weakened commercial performance, and the organization’s substantial future capital requirements.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants



