Key Takeaways
- LULU shares advance 5.16% to $98.95 amid ongoing revenue and profitability challenges.
- Net income drops to $329 million for the quarter as margins compress significantly.
- Cash and equivalents stand at $1.39 billion despite deteriorating sales trends.
- Quarterly free cash flow reaches $225 million even as sales performance weakens.
- Share repurchase program totals $1.16 billion as annual profitability declines.
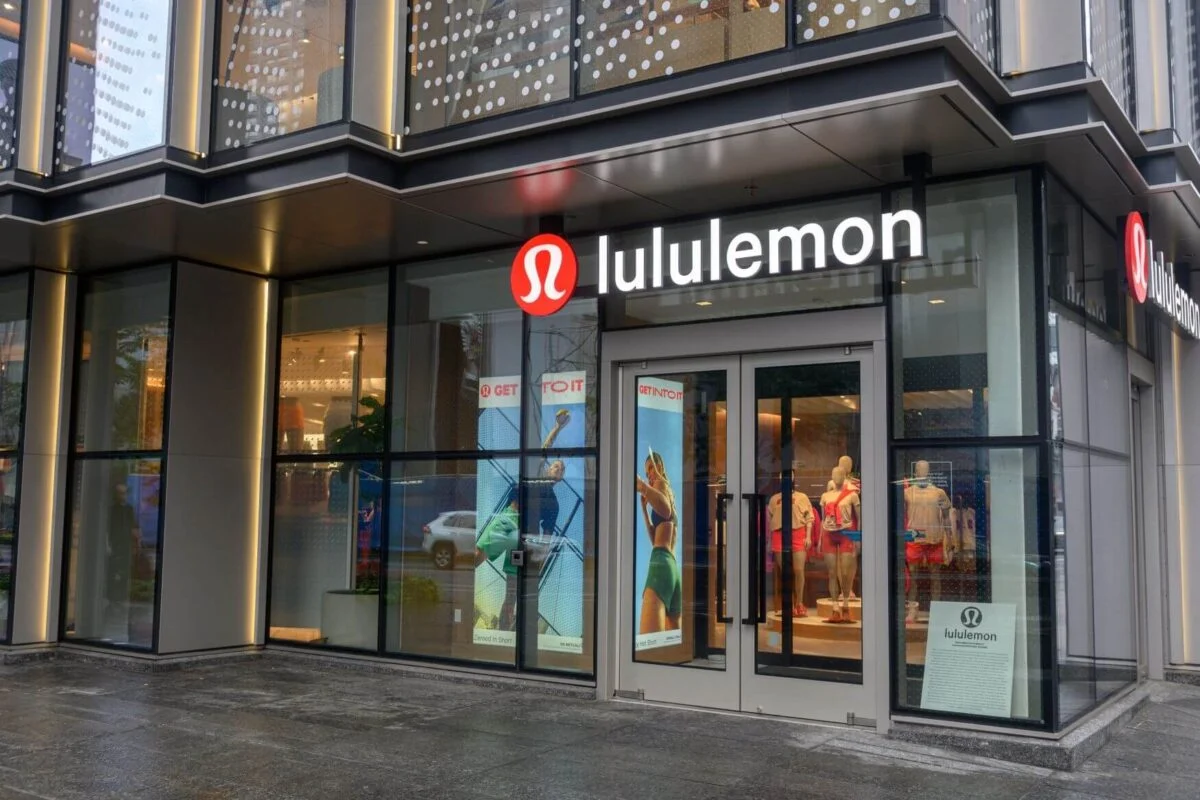
Shares of Lululemon Athletica (LULU) advanced 5.16% to close at $98.95 on Thursday, adding $4.86 despite ongoing deterioration in the athletic apparel company’s financial results. The retailer posted lower quarterly sales and profits while experiencing margin compression. However, the business maintained significant cash balances and produced healthy free cash flow despite the sales headwinds.
Lululemon Athletica Inc., LULU
Thursday’s gain comes after a prolonged period of share price weakness. Lululemon stock has tumbled 44.6% over the trailing twelve months, contrasting sharply with the S&P 500’s 17.3% advance. The underperformance highlights mounting pressure on the retailer as deteriorating revenue and profit metrics challenge its historical growth story.
On September 3, management lowered its full-year revenue guidance following disappointing business trends. Sales fell 4.3% year over year in the quarter that ended August 2, 2026. The downward revision underscores weakening demand and heightens focus on the company’s capacity to defend operating profitability.
Profit Margins Contract as Lululemon Earnings Weaken
Lululemon posted quarterly net income of $329 million, down from $371 million in the same period one year ago. The profit decline outpaced the revenue drop, demonstrating that expenses claimed a greater portion of sales. Operating efficiency deteriorated, pressuring profitability before accounting for non-recurring items.

The athletic apparel maker reported an operating margin of 18.8%, down from 20.7% in the prior-year quarter. A one-time tariff refund boosted the current margin by 5.6 percentage points. Stripping out that benefit, the underlying operating margin approximated 13.2%, revealing substantially weaker core profitability.
Annualizing the most recent quarter’s results would yield net income of roughly $1.32 billion. However, the quarter benefited from approximately $97 million in after-tax tariff refunds that inflated reported earnings. Removing those refunds produces an annualized profit figure near $930 million, well below the trailing twelve-month total of $1.42 billion.
Balance Sheet Strength and Cash Generation Remain Solid at Lululemon
Notwithstanding the earnings decline, Lululemon preserved a robust financial position during the latest quarter. The retailer reported cash and cash equivalents of $1.39 billion as of August 2, 2026. The company carries no bank debt or bond obligations, limiting its exposure to interest expense.
Lululemon’s primary long-term financial commitment consists of approximately $2.14 billion in lease liabilities. Over the past twelve months, the company produced $1.35 billion in free cash flow. That figure covered roughly 63% of total lease obligations, providing financial maneuverability despite decelerating business momentum.
Quarterly free cash flow strengthened as well, climbing to $225 million from $151 million in the comparable prior-year period. The improvement demonstrates that the retailer sustained cash generation even while revenue contracted and margins compressed. Its cash-producing capability remained more resilient than headline earnings suggest.
Lululemon deployed approximately $1.16 billion on share repurchases during the trailing twelve months. Those buybacks represented roughly 10.8% of the company’s market capitalization, signaling significant capital allocation toward shareholder returns. In September, management communicated that its 2026 repurchase spending would align with the prior year’s level.
The stock’s valuation shifts notably when adjusting for the one-time tariff benefits. Based on the October 14 closing price, shares traded at approximately 7.5 times trailing earnings, including the temporary refunds. Excluding those refunds and annualizing the quarterly results yields a multiple near 11.5 times earnings.
This annualized figure serves as a mechanical comparison rather than a projection of future performance. Lululemon typically generates its strongest quarterly sales in the period concluding in February, creating pronounced seasonal variations. The company’s current situation therefore blends deteriorating core profitability with ample liquidity, robust cash flow, and ongoing share repurchase activity.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants