


TLDR
- Continental equity markets advanced Friday with crude oil declining approximately 1%, reducing concerns over energy expenses.
- The STOXX 600 climbed 0.6%, positioning for a 0.1% weekly advance and breaking a three-session downward trend.
- Key indices including Germany’s DAX, France’s CAC 40, and Italy’s FTSE MIB recorded positive movements, with Italian equities leading.
- Market participants are monitoring the Trump-Xi diplomatic meeting in Washington for developments on trade relations and critical mineral supply networks.
- Notable stock movements featured Konecranes surging nearly 67% following a buyback announcement, while UBS climbed 3%.
European stock indices posted solid gains Friday, recovering from a turbulent trading week characterized by elevated government bond yields and heightened energy price concerns.
The continent-wide STOXX 600 benchmark advanced 0.6% throughout trading hours, positioning the measure for a modest 0.1% weekly advance. Such a performance would break a three-week declining pattern for the widely-tracked indicator.
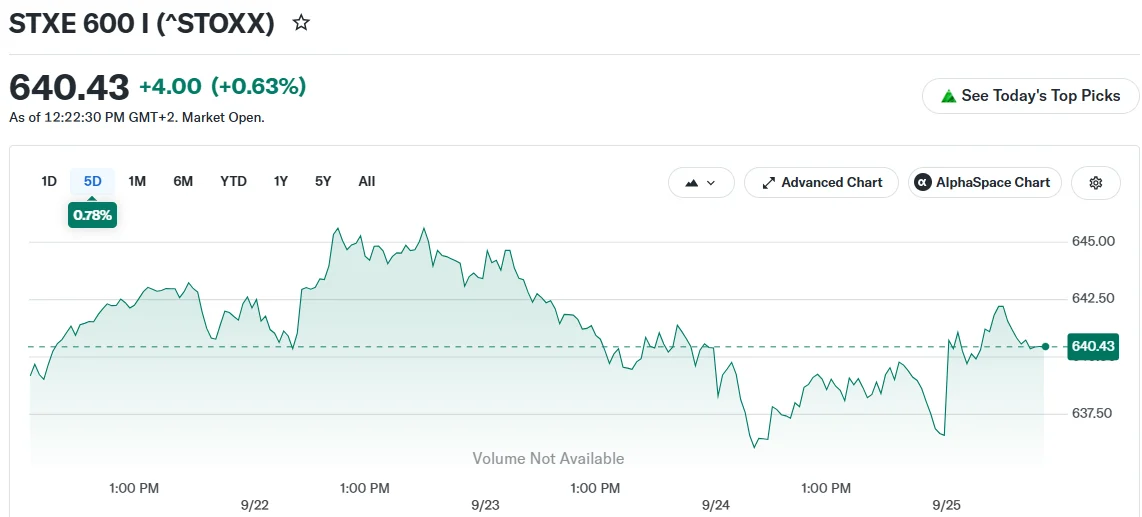
Regional benchmarks across major economies similarly trended upward. The German DAX increased 0.8%. The French CAC 40 registered a 0.2% advance. Britain’s FTSE 100 posted a 0.5% gain.
Italian equities outperformed continental peers, with the FTSE MIB climbing 1%.
Factors Behind The Rally
Declining crude petroleum prices provided significant support to equity valuations. Oil contracts decreased approximately 1% during Friday’s trading session.

Reduced oil prices typically benefit sectors with substantial energy consumption. Airlines, hospitality firms, and manufacturing companies experienced relief following pressure earlier this week stemming from inflation worries connected to elevated input costs.
Market participants also responded to reports indicating Washington and Tehran were discussing a staged diplomatic arrangement. Such an accord might reopen the strategically vital Strait of Hormuz and remove restrictions on Iranian maritime facilities. This diplomatic development contributed to petroleum price weakness.
Sovereign debt yields, which had climbed to multi-year peaks during earlier sessions, found stability. This stabilization allowed growth-oriented equities sensitive to borrowing costs an opportunity to regain ground.
Notwithstanding Friday’s recovery, the STOXX 600 continues trading in negative territory for the current month. A shortfall in European natural gas reserves and ongoing Middle Eastern trade uncertainties persist in constraining investor optimism.
Company Performance And News Flow
Corporate financial results provided additional market support throughout the week. Robust earnings from select companies helped counterbalance declines associated with the fixed-income selloff.
Konecranes emerged as one of the session’s strongest performers. The industrial machinery manufacturer surged nearly 67% after unveiling a capital return initiative through share repurchases.
UBS equity climbed 3% following a Semafor publication suggesting the financial institution had resumed discussions regarding potential restructuring of its Swiss domestic operations.
However, not all corporate news proved positive. Safestay experienced a decline exceeding 35%. The budget accommodation provider disclosed a 21% year-over-year reduction in advance reservations, attributing the weakness to challenging operating environments.
Financial analysts indicate investors maintain a cautious posture. Luke Davis, founder and chief market strategist at Bull Market Blueprint, suggested monetary authorities would probably adopt a wait-and-see approach regarding how declining energy expenses influence inflation metrics before implementing additional rate adjustments.
Market participants are simultaneously tracking high-level diplomatic exchanges between Washington and Beijing. President Donald Trump hosted Chinese President Xi Jinping for discussions in the American capital this week.
Lukman Otunuga, head of market research at FXTM, expressed skepticism regarding prospects for a significant agreement. Nevertheless, he noted the summit might represent a meaningful gesture toward eventual commercial cooperation.
Energy and foreign exchange markets continue demonstrating sensitivity to Middle Eastern geopolitical developments. Traders are evaluating the recent price correction against potential risks of renewed supply interruptions throughout the Persian Gulf region.
As of Friday’s opening, Euro Stoxx 50 futures contracts advanced 0.8%. Stoxx 600 futures registered a 0.7% increase in pre-session activity. Market attention is now shifting toward German consumer sentiment indicators, French labor market statistics, and Spanish economic output figures, with minimal corporate earnings announcements anticipated for the session.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants



