


Key Highlights
- Alphabet’s stock climbed more than 2% in Friday’s premarket session after advancing 1.3% the day before.
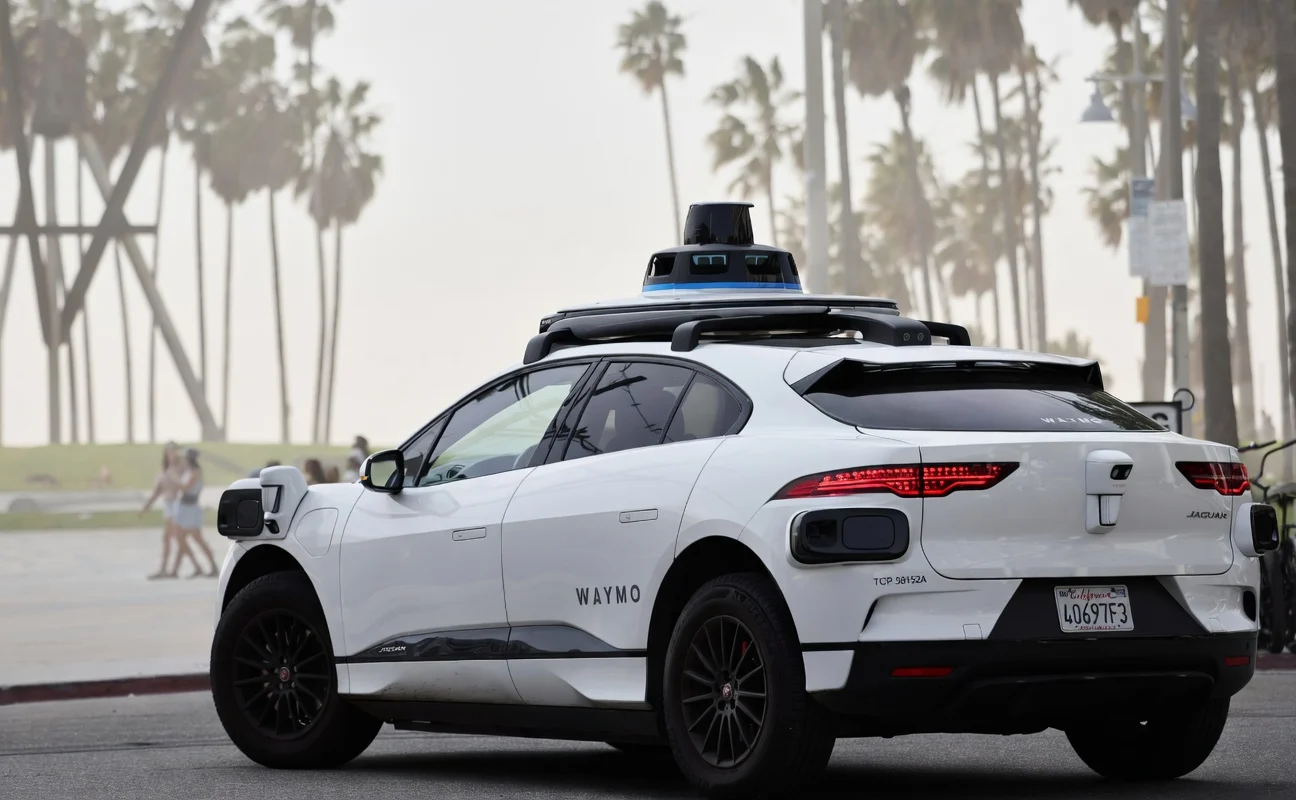
- The company’s autonomous vehicle division, Waymo, revealed plans for a 2028 driverless taxi service debut in Singapore, marking its Southeast Asian entry.
- Google secured a favorable outcome in its ad tech antitrust litigation, with a court imposing six-year behavioral mandates while rejecting forced divestiture.
- Tigress Financial Partners upgraded GOOGL’s price objective from $415 to $485, emphasizing artificial intelligence momentum in Search, Cloud, and YouTube segments.
- Analyst sentiment remains bullish with a Strong Buy rating consensus and a mean price projection of $429.31, suggesting 23.6% potential appreciation.
Shares of Alphabet (GOOGL) reached $347.33 during Friday’s pre-market hours on September 18, registering gains exceeding 2%. This upward momentum builds on the previous day’s 1.3% advance.
The stock’s morning rally stems from two primary developments: Waymo’s international expansion strategy and favorable developments in Google’s regulatory challenges.
On September 18, Waymo disclosed its intention to introduce autonomous ride-sharing operations in Singapore by 2028. The service will deploy a fleet of all-electric Jaguar I-PACE vehicles.
Throughout 2027, Waymo will conduct comprehensive road mapping and system validation in Singapore, preparing for varied conditions including seasonal monsoon patterns. Fleet size details for the initial rollout remain undisclosed.

This Singapore deployment represents Waymo’s inaugural Southeast Asian operation. The strategic move opens opportunities for customer acquisition and enhances the company’s international driving data collection capabilities.
Favorable Legal Outcome Alleviates Investor Concerns
Earlier this week, a federal court delivered its decision regarding Google’s ad tech monopoly allegations. The judgment mandates six years of operational restrictions and requires internal compliance oversight.
Importantly, the ruling rejected demands for forced divestiture or structural separation of Google’s AdX platform. This decision eliminated a significant investor concern and contributed to reduced selling pressure.
GOOGL has posted an 11% gain year-to-date. Following a May peak at $408.61 per share, the stock experienced a correction aligned with broader technology sector weakness.
Alphabet’s second quarter 2026 results showed advertising revenue of $81.63 billion, representing 14.5% annual growth. The Google Cloud division surged 82% to generate $24.77 billion during the identical timeframe.
Trailing twelve-month revenue totaled $445.87 billion, marking a 20% year-over-year increase. The company maintains a robust 50% return on equity while trading at a price-to-earnings multiple of 17.38.
Analyst Firm Elevates GOOGL Target to $485
Tigress Financial Partners announced on September 17 an increased price objective for GOOGL, moving from $415 to $485 while maintaining its Strong Buy recommendation.
The investment firm emphasized Alphabet’s commanding position in artificial intelligence, citing Gemini models, custom tensor processing units, and AI-powered services as catalysts for revenue expansion in core business segments.
Tigress acknowledged that near-term capital efficiency metrics may experience compression due to substantial AI infrastructure investments, but expects these expenditures to generate superior profitability over extended periods.
The analysis also underscored Alphabet’s financial strength, highlighting a net cash position. GOOGL maintains placement on both the firm’s Research Focus List and Focus Opportunity Portfolio.
Broader Wall Street sentiment aligns with this optimism. Drawing from 25 Buy recommendations and four Hold ratings issued over recent months, GOOGL earns a Strong Buy consensus designation. The collective average target of $429.31 indicates potential upside of 23.6% from present trading levels.
Trading activity for GOOGL averages approximately 23.3 million shares daily based on three-month data.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants



