


Key Takeaways
- Market participants anticipate a 25 basis point interest rate increase from the Federal Reserve on Wednesday, with probability ranging between 80-85%
- Wednesday morning brings retail sales figures for August, intensifying an already critical trading day
- Crude oil prices climbed above $100 per barrel following drone strikes that disabled a critical Saudi Arabian pipeline, heightening inflation worries
- Dario Amodei, chief executive of Anthropic, urged artificial intelligence companies to decelerate their progress, triggering selloffs in AI-related equities throughout Asian and European markets
- Japan’s central bank is anticipated to lift rates to 1.25%, whereas the Bank of England will likely maintain its current 3.75% level
The U.S. central bank commences its two-day monetary policy gathering on Tuesday, culminating in a rate announcement scheduled for Wednesday afternoon at 2 p.m. Eastern Time. Current market expectations place the likelihood of a quarter-point increase between 80% and 85%.
Arguments favoring tighter monetary policy gained momentum following last week’s inflation reports, which revealed persistent price pressures. August’s Consumer Price Index climbed 3.4% on an annual basis, mirroring the previous month’s figure. Producer price data similarly exceeded forecasts.
Federal Reserve Chairman Kevin Warsh will address reporters at 2:30 p.m. Eastern Time on Wednesday. Market participants will scrutinize his remarks for indications regarding the trajectory of monetary policy, as forward guidance may prove more consequential than the immediate rate adjustment.
Consumer Spending Data and Energy Prices Complicate Outlook
The Census Bureau releases August retail sales figures Wednesday morning at 8:30 a.m. Eastern Time. Unadjusted consumer expenditures declined 0.6% between June and July, and another disappointing report could signal mounting financial strain on households.
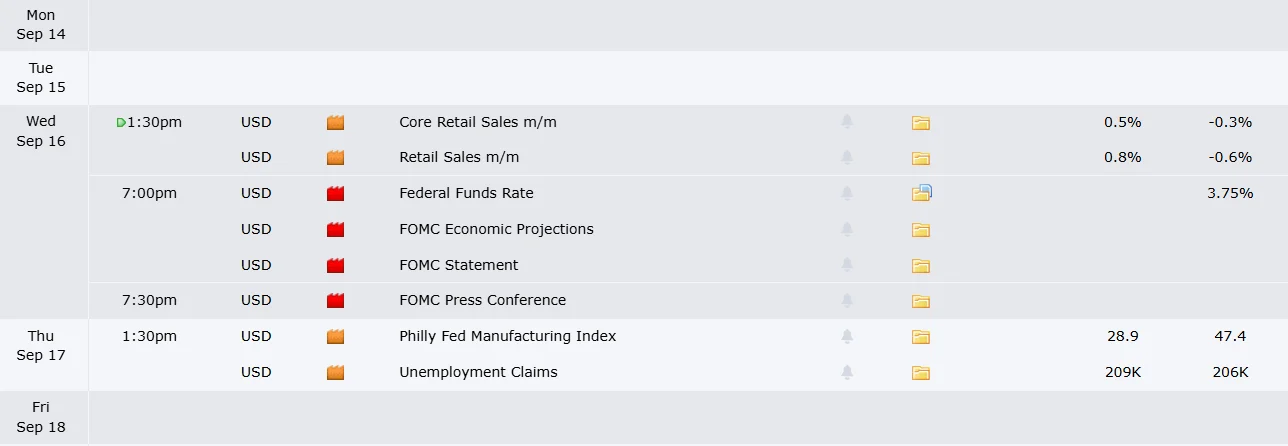
Conversely, robust consumer activity might reinforce the central bank’s rationale for additional rate increases. Regardless of the outcome, Wednesday promises to deliver heightened market volatility.

Energy markets introduced additional uncertainty. Brent crude momentarily exceeded $108 per barrel after drone assaults by Iran-aligned Houthi forces forced the closure of a major Saudi pipeline transporting approximately 4 million barrels daily.
Tensions surrounding the Strait of Hormuz have intensified. Scheduled diplomatic talks between Gulf nations and Iran were canceled, eliminating near-term prospects for resolving the supply disruption. Prior to the current crisis, roughly one-fifth of global oil and liquefied natural gas shipments traversed that strategic waterway.
Elevated energy costs contribute to broader inflation, creating challenges for monetary policymakers. Energy sector equities may benefit from higher prices, while transportation companies and consumer-facing businesses confront increased operational expenses.
Technology Sector Rattled by AI Development Concerns
Independent of macroeconomic developments, artificial intelligence-focused stocks declined throughout Asian and European trading sessions Monday. The downturn followed a weekend essay by Anthropic’s Dario Amodei advocating for reduced velocity in AI advancement.
Amodei referenced escalating risks associated with sophisticated AI system exploitation. The previous week, Anthropic disclosed that malicious parties had utilized its Claude platform for weapons-related research and fraudulent schemes.
His statements garnered endorsements from both Sam Altman of OpenAI and Elon Musk of xAI. Altman additionally confirmed OpenAI would forgo any initial public offering this year, citing safety priorities.
SoftBank experienced significant declines in Tokyo trading. Taiwan Semiconductor Manufacturing Company, SK Hynix, and Samsung Electronics likewise posted losses.
Deutsche Bank analysts suggested Amodei’s position might redirect AI capital allocation toward safety protocols and oversight frameworks, rather than diminishing aggregate investment levels.
Looking beyond monetary policy and artificial intelligence developments, Salesforce launches its Dreamforce gathering on Tuesday. Homebuilder Lennar publishes quarterly results Wednesday, while Carnival reports Thursday, providing insight into consumer travel appetites.
Major indices concluded the previous week in negative territory, with the Dow Jones Industrial Average retreating 1.6%. Year-to-date, the S&P 500 maintains approximately 12% gains.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants



