


TLDR
- Major index futures showed minimal movement Wednesday following record closing levels for both the S&P 500 and Nasdaq in the previous session.
- Minutes from the Federal Reserve’s September policy meeting will be released at 2 p.m. ET, potentially offering insight into the central bank’s interest rate trajectory.
- Brent crude futures climbed past the $100 per barrel threshold following renewed Houthi rebel strikes on Saudi Arabian targets, escalating Middle Eastern geopolitical risks.
- Bond yields edged upward across markets, with French sovereign debt attracting attention amid lingering fiscal concerns in Europe’s second-largest economy.
- Three technology giants—Nvidia, Apple, and Microsoft—now account for approximately 20% of the S&P 500’s total market capitalization, underscoring the market’s top-heavy nature.
US stock futures showed limited movement during Wednesday’s early session as market participants prepared for the release of Federal Reserve policy deliberations from last month.
The Dow Jones Industrial Average futures edged marginally lower. Meanwhile, contracts linked to both the S&P 500 and Nasdaq remained largely unchanged.
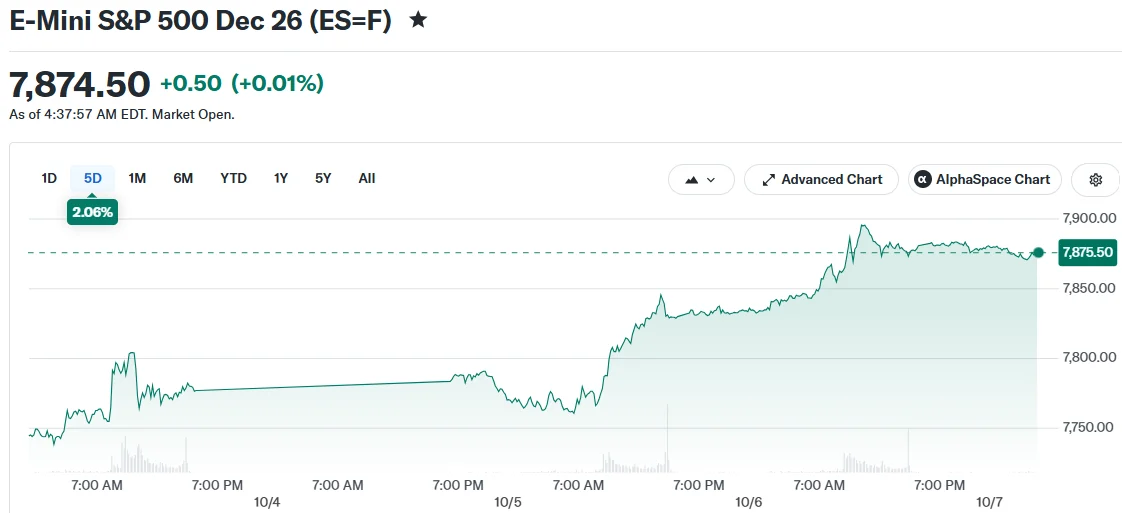
This subdued trading activity followed Tuesday’s session when both major benchmarks achieved fresh all-time peaks, propelled largely by continued enthusiasm surrounding artificial intelligence technologies.
Fed Minutes Could Signal the Next Move on Rates
The central bank’s September meeting readout is scheduled for release at 2 p.m. ET on Wednesday. Market participants are eager to determine whether policymakers view the previous rate increase as an isolated action or part of a continuing tightening cycle.
According to Tuesday’s pricing, futures markets assigned roughly 20% probability to an additional rate hike during the Fed’s upcoming October gathering scheduled for next week. Today’s minutes release has the potential to recalibrate those expectations.

Government debt yields retreated modestly during Tuesday’s trading but continued hovering near levels not witnessed in multiple decades. The benchmark 10-year US Treasury yield was recently quoted around 5.3%.
In European markets, French government bond yields climbed again on Wednesday, though they remained beneath the elevated levels observed last week when concerns about Paris’s fiscal position intensified.
Oil Prices Stay High on Middle East Tensions
Brent crude futures maintained trading above the $100 per barrel mark Wednesday morning, with prices hovering near $101 in recent transactions.
The continued strength in oil markets followed additional strikes launched by Houthi forces based in Yemen against targets in Saudi Arabia, perpetuating elevated regional security risks throughout the Middle East.
Rising energy costs represent an additional variable for market watchers to monitor during the current trading week, as petroleum prices directly influence the inflation metrics that Federal Reserve officials scrutinize when making policy determinations.
This year’s equity market appreciation has been notably concentrated among a limited cohort of large-cap technology companies. The combined market capitalization of Nvidia, Apple, and Microsoft now represents approximately one-fifth of the entire S&P 500 index.
This concentration dynamic means that price movements in just a few individual securities can substantially influence the broader index’s performance. Market strategists have identified this characteristic as a significant contributor to the benchmark’s ability to reach successive record levels.
Nvidia shares registered modest gains in pre-opening trading on Wednesday. The semiconductor manufacturer has emerged as a primary beneficiary of the ongoing rally driven by corporate investment in artificial intelligence infrastructure.
Corporate earnings reports remain on the calendar this week, with both Levi Strauss and Applied Digital scheduled to announce quarterly results on Wednesday.
Market participants will monitor those financial releases in conjunction with the Federal Reserve’s meeting minutes, as either development carries the potential to influence trading before Wednesday’s closing bell.
During early Wednesday price action, the S&P 500 E-Mini contract traded marginally higher near the 7,875 level. Both the Nasdaq 100 E-Mini and Dow E-Mini contracts declined slightly, while the 10-year Treasury yield registered at 5.309%.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants



