


TLDR
- European equities rebounded Friday following Thursday’s three-month low.
- The STOXX 600 posted gains despite tracking toward its steepest weekly decline since April.
- French 10-year government bonds reached yields not seen since 2002 as budget fears escalate.
- The euro touched its weakest position versus the dollar since 2025.
- IG Group stock plunged while JD Wetherspoon surged following corporate updates.
European equity markets staged a recovery Friday, rebounding from the previous session when benchmark indices touched their lowest points in three months.
The pan-European STOXX 600 index climbed 0.9% during Friday trading. Meanwhile, the STOXX 50 advanced 1.1%, supported by declining crude oil prices and easing pressure on government debt markets.
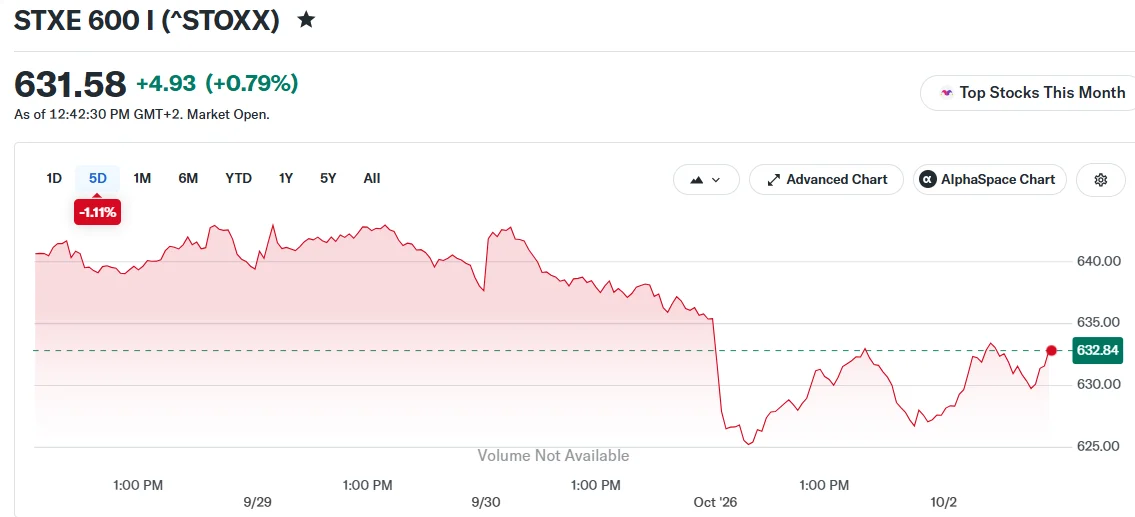
Despite Friday’s positive momentum, European markets have endured a challenging week. The STOXX 50 is tracking a 2% weekly decline, while the STOXX 600 has shed 1.9%. Both indices are heading toward their weakest weekly closes since April.
Germany’s DAX index advanced 0.9% Friday. France’s CAC 40 gained 0.6%. The FTSE 100 in London remained largely flat.
French Bond Yields Hit Multi-Decade High
Earlier weekly losses stemmed from a significant selloff in European sovereign debt markets. Investors grew increasingly concerned about France’s fiscal position after officials unveiled the government’s 2027 budget proposal.

Yields on France’s 10-year government bonds climbed to levels last witnessed in 2002. Market participants are demanding higher compensation for holding French debt amid uncertainty surrounding the nation’s expenditure plans.
The spread between French and German 10-year yields expanded beyond 140 basis points—the widest differential recorded since the 2012 European sovereign debt crisis.
These fiscal pressures weighed heavily on the euro. The shared currency declined to its weakest exchange rate against the U.S. dollar since 2025.
Reuters reported Friday that European Union member states were discussing a French proposal to tap strategic diesel reserves. Brent crude oil prices retreated toward $99 per barrel on the news. Declining energy costs helped alleviate inflation concerns and reduced upward pressure on government bond yields, including those in France.
Inflation Data and Jobs Report Ahead
Market participants are awaiting the preliminary September inflation figures for the Eurozone. Analysts anticipate the reading will accelerate to 3.6% from August’s 3.2%. Rising energy expenses tied to Middle Eastern conflict are considered the primary catalyst.
Focus is simultaneously shifting across the Atlantic. The U.S. September employment report is approaching. Robust jobs data could reinforce the Federal Reserve’s position on maintaining elevated interest rates for an extended period. Such an outcome might push global bond yields further upward.
Individual equity performance varied dramatically this week. Trading platform operator IG Group tumbled as much as 27% at its session low, touching levels not seen since April 2025. Management indicated third quarter revenue would approximate £240 million—representing a 14% year-over-year decline.
JD Wetherspoon shares moved in the opposite direction. The pub operator’s stock surged over 8% after reporting improved recent sales performance. Management stated full year earnings should align with market expectations, despite posting a 28% annual profit decline attributed to elevated operating costs.
Technology and industrial sectors paced Friday’s advance. ASML Holding climbed 2.4%. Siemens increased 1.1%. Inditex appreciated 2.2%.
Infineon surged 5.9%. Thyssenkrupp rallied 4.5%. Stellantis advanced 4.1%. These stocks ranked among the STOXX 600’s strongest performers.
Sanofi registered the index’s steepest decline, falling 3.2%.
Traders will closely monitor upcoming inflation and employment releases for signals heading into the following week.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants



