


Key Takeaways
- Major U.S. stock indices declined Thursday, erasing early session gains as bond yields continued their ascent.
- The 10-year Treasury yield climbed to approximately 5.3%, marking a fresh multi-decade peak.
- Micron Technology surpassed earnings forecasts and upgraded its forward guidance, though shares showed minimal movement.
- Manufacturing sector data revealed weaker-than-anticipated expansion alongside increasing price pressures.
- Weekly jobless claims declined for the fourth consecutive week, indicating continued labor market resilience.
U.S. equity markets experienced downward pressure Thursday as escalating bond yields dominated investor attention, eclipsing an impressive quarterly report from Micron Technology. The decline occurred during the initial trading session of October.
The Dow Jones Industrial Average declined approximately 0.5%. Both the S&P 500 and Nasdaq Composite retreated roughly 0.3% during the session.
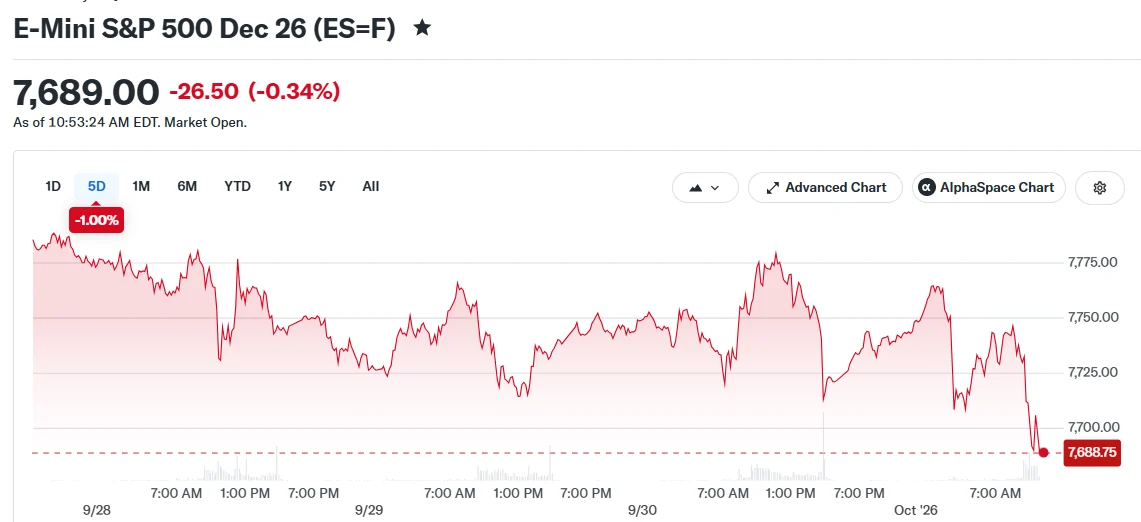
The major benchmarks had opened with positive momentum earlier in the session. However, those advances evaporated as mounting concerns from the bond market intensified throughout the morning hours.
Treasury Yields Continue Upward Trajectory
The benchmark 10-year Treasury yield advanced once again Thursday, touching approximately 5.3%. This level represents a fresh multi-decade milestone for the key rate.
The move followed a challenging three-month period for fixed-income securities. Bond markets had just concluded their most difficult quarterly stretch in decades as September came to a close.

Elevated yields increase the cost of capital for businesses and consumers. Additionally, they can diminish the relative appeal of equities, as fixed-income instruments offer more competitive returns with lower risk profiles.
Interest rate-sensitive sectors bore the brunt of the selling pressure. Materials, real estate, and financial services stocks were among the session’s worst performers.
Technology and energy were the only sectors maintaining positive territory. At certain points during morning trading, fewer than one-third of S&P 500 constituents were showing gains.
Manufacturing Reports Signal Slowdown
Thursday brought a pair of manufacturing sector reports, both indicating softer expansion than economists had anticipated.
The S&P 500 Manufacturing Purchasing Managers Index registered 55.9 for September. This figure fell short of the preliminary reading of 57.
A concurrent release from the Institute for Supply Management revealed manufacturing input prices accelerated notably in September. Increasing production costs can compress corporate margins and reignite inflation anxieties.
These data points emerged following a disappointing end to the third quarter. The Dow recorded declines for both September and the full three-month period, while the Nasdaq posted quarterly gains.
Micron Technology delivered fourth-quarter results that exceeded analyst projections. The memory chip manufacturer also elevated its first-quarter outlook.
Yet despite the robust performance, Micron’s stock price remained essentially flat throughout the session. Market participants appeared preoccupied with fixed-income market dynamics rather than individual corporate results.
Other semiconductor and technology stocks displayed varied performance. One leading chipmaker posted modest gains following a strong September, while another semiconductor name declined after rallying 30% during the previous month.
Employment data continued to reflect market stability. First-time unemployment claims decreased for the fourth consecutive week according to the latest release.
An additional report from Challenger, Gray & Christmas on corporate restructuring revealed that companies disclosed fewer planned workforce reductions in September. However, organizations have remained cautious about expanding their employee bases.
These employment indicators precede Friday’s highly anticipated monthly jobs report. That comprehensive release will provide deeper insights into hiring patterns and unemployment rate movements.
Nike is scheduled to announce quarterly results following Thursday’s closing bell. The athletic apparel giant’s shares have been hovering near their lowest valuations since 2014, with market watchers seeking evidence of operational improvement.
As late morning trading progressed, the 10-year yield stood at 5.33%, while the 2-year yield retreated to 4.852%. The Dow declined approximately 328 points, with the S&P 500 down 0.36% and the Nasdaq lower by 0.31%.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants



