


TLDR
- Major equity indexes finished Friday’s session in positive territory following a surprisingly weak September employment report that dampened expectations for additional Fed tightening this month.
- September payroll growth registered just 29,000 new positions, marking the weakest monthly expansion in 2024, as joblessness climbed to 4.2%.
- Longer-dated Treasury yields continued their ascent, with benchmark 10-year and 30-year rates reaching levels not observed since the early 2000s.
- Nike’s equity tumbled 3.6% following disappointing quarterly results and cautious forward guidance, while Tesla advanced 4.7% on better-than-expected vehicle deliveries.
- Crude prices declined over the week after G7 members committed to tapping strategic petroleum reserves to stabilize global energy markets.
Wall Street wrapped up Friday’s trading session with solid gains, capping a choppy week for equity markets. The S&P 500 advanced 0.8% while the Nasdaq Composite surged 1.2%, briefly establishing a fresh intraday peak.
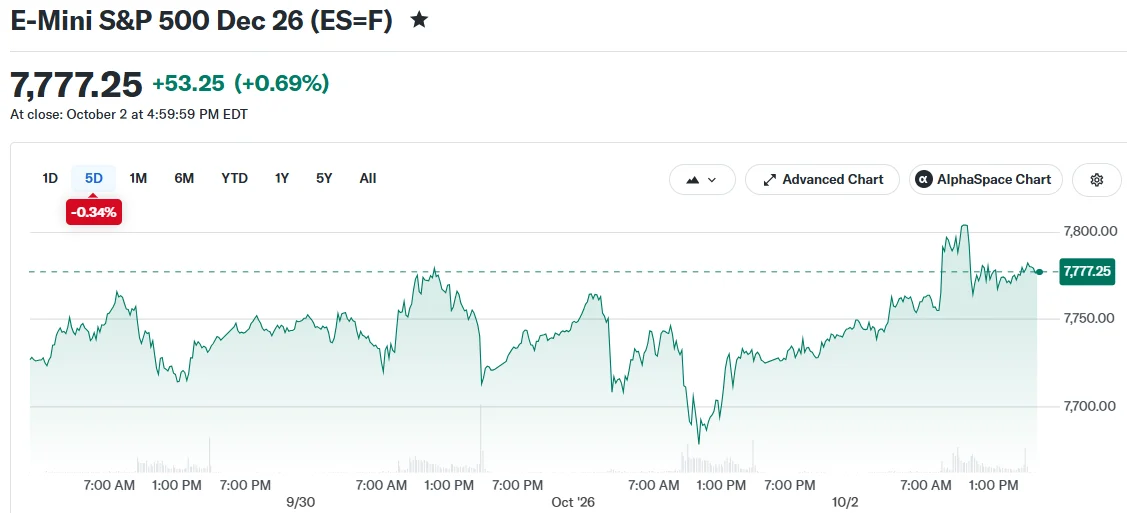
The Dow Jones Industrial Average posted a 0.5% gain for the session. However, across the entire five-day period, the Nasdaq stood alone as the only major benchmark closing with weekly gains.
Employment Data Misses Expectations
Friday’s rally materialized after the release of a disappointing September employment situation report. According to the U.S. Bureau of Labor Statistics, employers added merely 29,000 nonfarm positions during the month.
The figure fell dramatically short of the 89,000 additions analysts had anticipated. It represented the most sluggish pace of job creation recorded in any month throughout 2024.
Downward revisions to July and August employment figures subtracted an additional 60,000 positions from previous estimates. Meanwhile, the unemployment rate ticked upward to 4.2% from the prior month’s 4.1% reading.

Compensation growth also decelerated. Average hourly earnings inched up a mere 0.1% on a monthly basis and expanded 3% year-over-year, representing the most tepid annual advance since May 2021.
Market participants interpreted the lackluster employment data as evidence that the Federal Reserve has flexibility to maintain its current policy stance at the upcoming late-October meeting. The CME FedWatch tool indicated probability of an October rate increase dropped to approximately 23%.
Nevertheless, certain central bank officials have indicated additional monetary tightening might prove necessary to contain inflationary pressures. Dallas Fed President Lorie Logan suggested rates may require at least a 50-basis-point elevation.
Treasury Market Continues Selling Pressure
Despite diminishing rate hike expectations, fixed-income markets painted a contrasting picture. Longer-maturity Treasury yields extended their upward trajectory throughout the week.
The benchmark 10-year note reached its loftiest yield since 2002. The 30-year bond climbed to a level last witnessed in May of that same year.
Market observers attributed the yield surge to multiple converging factors. These encompass expanding government debt issuance, substantial corporate borrowing to finance artificial intelligence infrastructure investments, and persistent inflation anxieties.
Oil prices exhibited an inverse pattern. Brent crude retreated 4.4% across the week while West Texas Intermediate slipped 3.2%.
The energy price decline followed a coordinated announcement from G7 nations pledging to release as much as 100 million barrels from strategic petroleum stockpiles. The initiative aims to promote stability in worldwide energy markets.
Individual Stock Movements: Nike And Tesla
Nike shares declined 3.6% after the athletic apparel giant disclosed quarterly revenue that fell short of projections. Management also issued conservative outlook statements for the fiscal period ahead.
Company executives announced plans for additional workforce reductions alongside a restructuring of international operations. Nike has confronted intensifying competitive pressures and disappointing sales performance in the Chinese market.
Tesla charted an opposite course, climbing 4.7%. The electric vehicle manufacturer reported third-quarter deliveries totaling 486,532 units, surpassing Wall Street consensus estimates of roughly 462,000 vehicles.
In the week ahead, market participants will turn their attention to forthcoming inflation measurements. The consumer price index and producer price index releases are slated for October 14 and 15 respectively.
The Federal Reserve’s subsequent monetary policy determination is calendared for October 28.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants



