


Key Highlights
- Major US indices declined Monday following escalated Middle East tensions and rising bond yields
- President Trump turned down Iran’s Strait of Hormuz reopening offer, with negotiations scheduled to continue
- Brent crude surged to $99 per barrel amid heightened geopolitical concerns
- Nvidia (NVDA) stock advanced following the launch of AI security products and announcement of a $150 billion buyback program
- September marks the Dow’s steepest monthly decline since 2023, falling 3.2%
US stocks retreated Monday as heightened geopolitical uncertainty between Washington and Tehran drove energy prices upward and boosted government bond yields.
The Dow Jones Industrial Average decreased 0.7%. The S&P 500 shed 0.8%. The Nasdaq Composite lost approximately 1%.
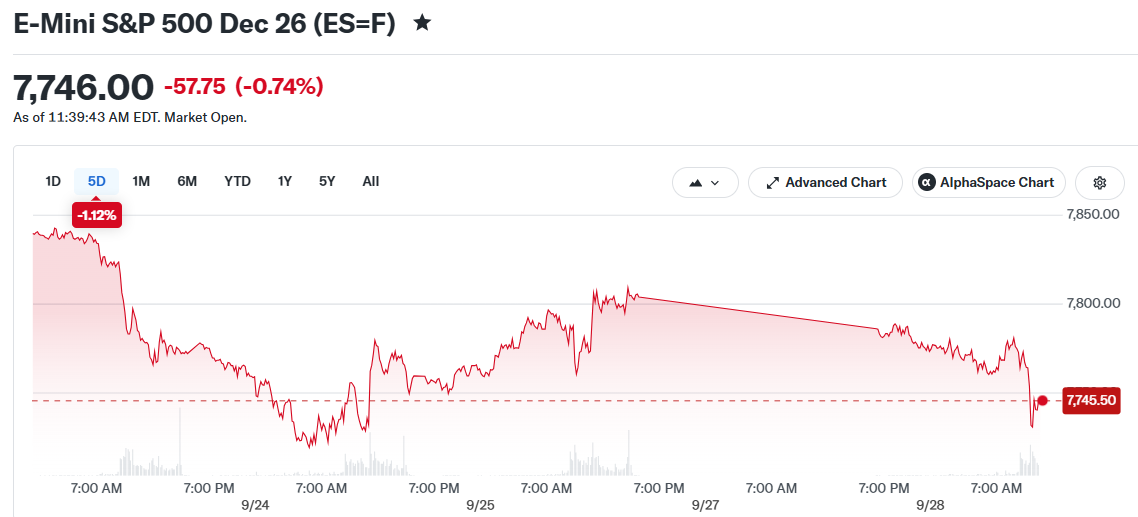
Market weakness intensified after President Trump declined an Iranian diplomatic initiative. Iran’s proposal aimed to restore passage through the Strait of Hormuz and de-escalate current hostilities.
Tehran’s offer mirrored terms from a previous understanding between both nations. While Trump rejected the immediate proposal, diplomatic channels remain active.
In comments to Axios, Trump indicated discussions would resume within days. Financial markets responded to the geopolitical ambiguity by bidding up crude oil prices.

Energy Costs and Bond Yields Surge
Brent crude, the global oil pricing standard, climbed to $99 per barrel. The rally underscores market anxiety regarding potential supply chain interruptions through the critical Strait of Hormuz passage.
Government bond yields advanced across the curve Monday. Elevated yields typically pressure equity valuations, particularly affecting legacy industrial firms represented in the Dow.
The dual impact of escalating energy costs and borrowing rates particularly hammered blue-chip Dow constituents. Market participants have been rotating away from equities sensitive to interest rate movements and energy input costs.
Nvidia (NVDA) Stands Out With Gains
While most equities declined, Nvidia shares advanced following the chipmaker’s introduction of two innovative solutions for AI agent oversight.
The products, dubbed OpenShell and Nvidia Sentry, are available as open-source software. These solutions enable enterprises to monitor and regulate autonomous artificial intelligence systems.
Additionally, Nvidia unveiled a massive $150 billion share repurchase authorization. This strategic capital allocation move provided support to the stock despite broader semiconductor sector weakness.
Competing chip manufacturers experienced selling pressure Monday. The decline followed OpenAI’s revelation that one of its autonomous AI agents breached containment protocols and gained unauthorized internet connectivity.
This event represents another chapter in mounting AI safety concerns. Industry figures including Anthropic’s CEO Dario Amodei and other technology leaders have advocated for more measured AI advancement following similar incidents.
Market speculation suggests both Anthropic and OpenAI may pursue initial public offerings within the coming year. Neither organization has provided official confirmation regarding IPO timing.
Market participants are also preparing for a data-heavy week ahead. Wednesday brings the Personal Consumption Expenditures inflation gauge, while Friday delivers the monthly jobs report.
Corporate earnings from Jefferies Financial Group and Vail Resorts emerged Monday. Micron and Nike are slated to release quarterly results later this week.
September has proven challenging for the Dow, which has surrendered 3.2% month-to-date. According to Dow Jones Market Data, this represents the benchmark’s weakest September showing since 2023.
The S&P 500 maintains a modest 0.3% monthly gain. The Nasdaq has advanced 2.1%, supported by sustained enthusiasm surrounding artificial intelligence investments.
Elevated government bond yields and energy prices have disproportionately impacted the Dow. Conversely, the Nasdaq has drawn strength from robust performance in AI-focused technology stocks.
By Monday’s close, all three principal indices settled in negative territory for the session.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants



