


TLDR
- Goldman Sachs upgraded Palantir to Buy from Neutral with a $230 price target.
- The target implies about 18% upside from Wednesday’s close of $194.12.
- Palantir stock gained 2% to $198.78 on Thursday, pushing toward chart resistance near $204.
- RSI sits near 70, approaching overbought levels after a sharp rally since August.
- 71% of analysts tracking Palantir rate it Buy or Overweight.
Palantir Technologies stock rose 2% to $198.78 on Thursday, extending a rally that’s put the shares within range of a key resistance zone. The move followed a ratings upgrade from Goldman Sachs that added fresh fuel to an already strong run.
Palantir Technologies Inc., PLTR
Goldman analyst Gabriela Borges lifted her rating to Buy from Neutral and set a $230 price target. That implies roughly 18% upside from Wednesday’s close of $194.12.
Borges expects Palantir’s addressable market to keep growing. She points to sovereign AI as a major driver, with governments and enterprises wanting to keep data under local control rather than handing it to public cloud providers.
Chart Check: Momentum Cooling, Resistance Ahead
The stock has been climbing inside a rising wedge since its August breakout, with the $160 zone now holding as support below. Price is pressing against resistance in the $200 to $204 range, a level the stock hasn’t closed above yet.
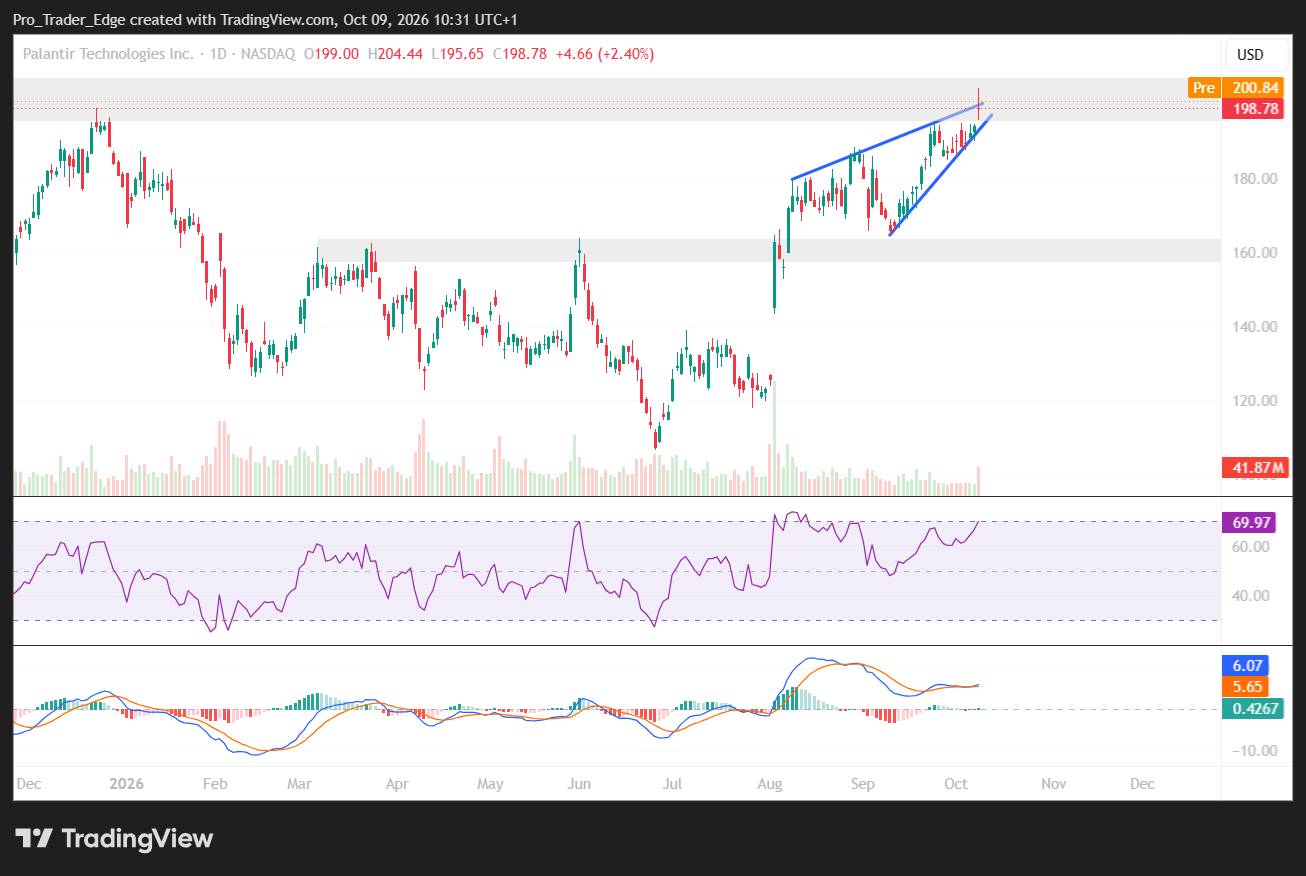
RSI reads 69.97, just shy of overbought territory. That leaves some room to run but not a lot. MACD stays in bullish territory, though the histogram has flattened compared to August’s sharper push, a sign momentum is cooling even as price grinds higher.

What to watch: a clean break above $204 could open the door to fresh highs, while a slip below $180 would signal the wedge is breaking down, with $160 as the next support test.
Other analysts share Goldman’s optimism. D.A. Davidson’s Gil Luria rates the stock Buy with a $250 target, arguing that trust concerns around major AI labs are pushing customers toward Palantir as a data control layer.
Borges also flagged a shift toward custom AI tools built for specific jobs, rather than generic chatbot wrappers. She cited CrowdStrike’s new SafeMind system and Datadog’s machine learning forecasting as examples of that trend spreading across software.
Valuation Still a Talking Point
Palantir’s forward-deployed engineering model, where staff work directly with clients to tailor the software, remains central to the bull case. Borges says the company has gotten efficient enough to automate parts of that process using AI.
She added that industries with thinner in-house tech talent could be fertile ground for Palantir, since those firms can’t easily replicate the work internally.
Valuation remains the sticking point critics keep coming back to. The stock traded above 200 times forward earnings last October before cooling off.
As of Wednesday’s close, Palantir sits at 91.1 times forward earnings. That’s still far above the S&P 500’s 19.4 multiple and the Nasdaq Composite’s 22.5.
Earnings growth is expected to help close that gap. Analysts project EPS of $1.60 for 2026, climbing to $14.38 by 2030, an average annual growth rate above 70%.
Of 35 analysts tracked by FactSet, 25, or 71%, rate Palantir Buy or Overweight. That’s well above the 55% to 60% average Buy ratio typical for S&P 500 names.
Palantir shares are up 16% year-to-date, trailing the Nasdaq-100’s 24% gain. Over the past six months, though, the stock has surged 38%.
Goldman noted Palantir is running at an $8 billion revenue pace with growth near 100%, backed by trailing twelve-month revenue growth of 79% and an 85% gross margin.
UBS also lifted its target to $250 recently, citing AI demand momentum, while Yorkville Ives started coverage with an Outperform rating and a $250 target.
Rosenblatt reiterated its Buy rating and $225 target following Palantir’s rollout of its AI-powered SMART system for the Federal Aviation Administration, the company’s first U.S. deployment of the tool.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants



