


Quick Overview
- Wednesday brings the August Personal Consumption Expenditures report, marking the initial inflation assessment following the Federal Reserve’s rate increase in September.
- Friday’s September employment data is projected to show 100,000 new positions added, with the jobless rate expected to remain steady at 4.2%.
- Micron Technology releases its fiscal fourth-quarter performance Wednesday, with Wall Street analysts projecting earnings of $31.52 per share and revenue around $51.07 billion.
- Additional earnings releases from CarMax, Carnival, Nike, and Accenture will provide insight into consumer behavior and corporate expenditure patterns.
- Last week saw the 10-year Treasury yield finish at 5.17%, while home loan rates reached their peak since January 2025.
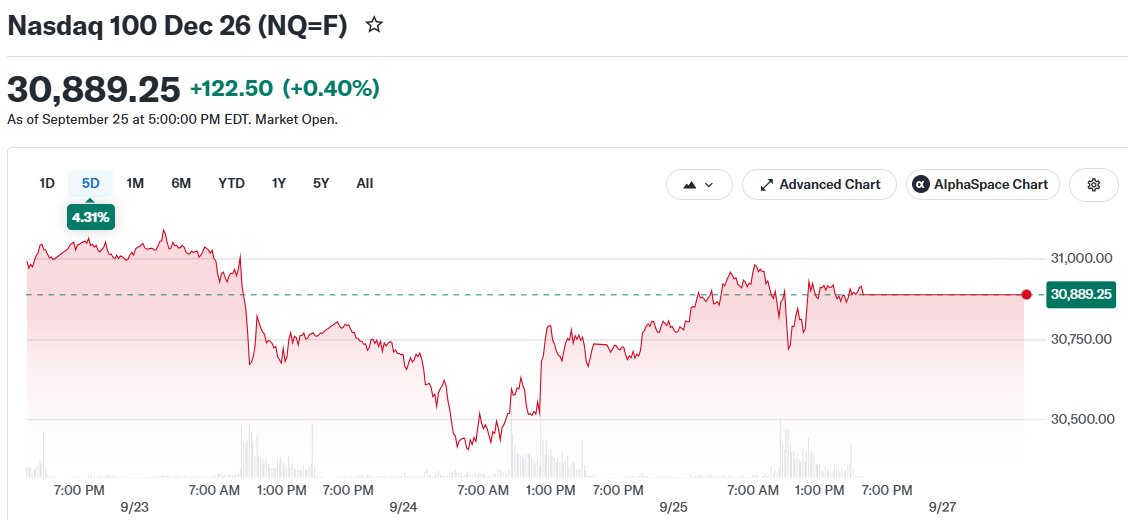
Wall Street begins the trading week with attention fixed on inflation metrics, employment numbers, and several significant earnings announcements. The previous week delivered gains across all three primary indices. The Nasdaq approached an all-time high, while the Dow ended a three-week decline.
Wednesday marks the release of the Bureau of Economic Analysis’s August Personal Consumption Expenditures price index. This metric represents the Federal Reserve’s favored inflation measurement. The data represents the initial inflation assessment following the central bank’s September 16 interest rate adjustment.
The previous core PCE report showed a 3.3% annual increase. This figure remains significantly above the Fed’s 2% objective. An unexpectedly elevated reading could increase the probability of an additional rate adjustment in October.
Employment Statistics and Consumer Sentiment Take Center Stage
Tuesday brings an update to the Conference Board’s Consumer Confidence Index. August witnessed a decline in the index, despite modest improvements in American attitudes toward employment prospects.
Friday delivers the September employment report. Reuters’ economist survey anticipates 100,000 new positions added to the economy. The unemployment figure is projected to hold at 4.2%.

August’s hiring figures exceeded projections, though the improvement wasn’t substantial enough to alter this year’s trend of modest hiring and limited layoffs. A report showing greater strength could bolster arguments for another Federal Reserve rate increase.
Consumer outlook has faced headwinds. The University of Michigan survey registered sentiment at the second-lowest point in the survey’s 74-year existence. Home financing costs compound this pressure, with 30-year fixed mortgage rates ascending to 7.45%, marking the highest level since January 2025.
Quarterly Results From Micron, CarMax, and Nike
Wednesday brings Micron Technology’s fiscal fourth-quarter earnings announcement. Wall Street anticipates $31.52 per share with approximately $51.07 billion in revenue. The memory chip manufacturer serves as a key indicator for demand related to artificial intelligence data centers.
Tuesday features CarMax’s fiscal second-quarter earnings. An activist shareholder urged the retailer earlier this year to explore used vehicle price reductions. The results may reveal whether pricing challenges have diminished.
Carnival Corporation launches the week’s earnings season Monday. Projections call for $1.35 per share with $8.39 billion in revenue. Cruise industry spending remained resilient throughout the summer despite consumer cutbacks in other travel categories.
Wednesday afternoon brings Nike’s fiscal first-quarter announcement. Estimates stand at $0.44 per share with $11.33 billion in revenue. The athletic apparel giant’s previous quarterly disclosure revealed a 12% decline in Chinese market sales.
Thursday features Accenture’s earnings, with projections of $3.18 per share on $18.03 billion in revenue. The consulting giant recently established a five-year artificial intelligence safety collaboration with Anthropic.
McCormick and Company also presents results Wednesday, with expectations of $0.76 per share on roughly $1.98 billion in revenue. The seasoning company is pursuing a merger with Unilever.
Treasury Yields and Overall Market Landscape
The 10-year Treasury yield concluded last week at 5.17%. The 30-year yield climbed to its loftiest point in over two decades. Elevated yields diminish the present-day valuation of companies’ future earnings.
September proved negative for eight of the S&P 500’s 11 sectors. An equal-weighted index version declined approximately 4% for the month, demonstrating the market’s advancement has depended substantially on a limited number of large technology companies.
Gold settled near $4,322.40, crude oil traded around $92.79, and Bitcoin finished close to $83,809. The VIX volatility index, which measures anticipated market fluctuations, dropped to 14.87.
Multiple corporations enter ex-dividend status this week, including Cisco Systems, Deere, and Bristol-Myers Squibb. Market participants will balance this week’s employment and inflation releases against elevated bond yields to determine the market’s subsequent trajectory.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants



