


Key Highlights
- Brent crude declined 0.8% to $97.24 per barrel while WTI dropped 1% to $89.50 on Thursday.
- Gulf region crude shipments reached 16.328 million barrels daily in September, marking the highest output since hostilities commenced in February.
- Saudi Arabia resumed loading operations at Yanbu following the restoration of its East-West pipeline infrastructure.
- Major financial institutions such as Goldman Sachs, J.P. Morgan and Morgan Stanley have elevated their crude price projections through year-end.
- U.S. diesel reached an all-time high of $6.53 per gallon amid discussions of potential export restrictions.
Oil prices retreated on Thursday following Wednesday’s gains. Market participants are monitoring emerging evidence of Middle East crude production recovery. However, uncertainty persists regarding the sustainability of this upturn.
December Brent crude futures declined 0.8% to settle at $97.24 per barrel. This figure was captured at 02:41 ET. U.S. West Texas Intermediate crude decreased 1% to $89.50 per barrel.
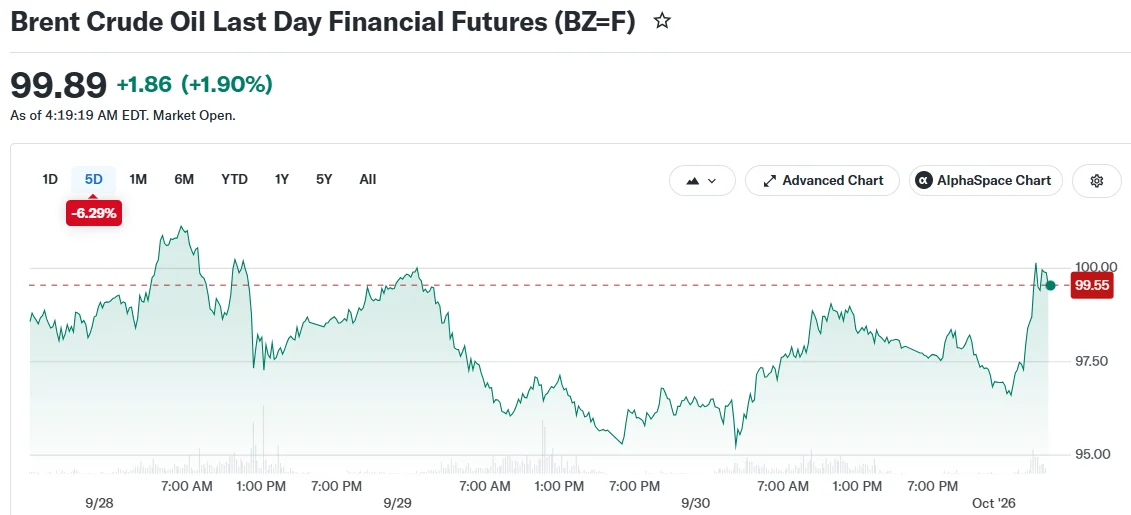
Wednesday marked the expiration of the front-month Brent contract. It closed at $103.50 during the previous trading session.
September witnessed Brent climbing approximately 14%. This represented its most robust monthly performance since July. WTI increased roughly 5% during the identical period.
Gulf Region Shipments Stage Recovery
Recent statistics indicate Gulf exports are staging a comeback. September saw Middle East crude shipments hit 16.328 million barrels daily. This marks the peak level recorded since February’s outbreak of regional hostilities, based on intelligence from data analytics company Kpler.

Saudi Arabia has also restarted tanker loading activities at Yanbu, its Red Sea terminal. This development followed the kingdom’s successful repair and restart of its East-West pipeline infrastructure, which sustained earlier damage.
Nevertheless, regional output continues tracking below pre-conflict benchmarks. Kpler’s analysis reveals September shipments lagged February volumes by approximately 3.2 million barrels daily. This gap leaves markets vulnerable to additional supply shocks.
Diplomatic efforts continue shaping the narrative. Iran announced Wednesday it had received Washington’s response to its most recent ceasefire initiative. This development came after President Donald Trump dismissed a previous proposal connected to Strait of Hormuz reopening conditions.
Financial Institutions Elevate Price Projections
A Wall Street Journal survey reveals leading banks have increased their crude price expectations. Goldman Sachs, J.P. Morgan and Morgan Stanley now project Brent crude will average $90.22 per barrel during the fourth quarter. WTI is forecast to average $85.47 per barrel.
These projections significantly exceed previous estimates of $78.92 and $74.62 per barrel respectively. The upward revision reflects persistent concerns about supply interruptions linked to the Iran situation.
Full-year projections now place Brent at an average of $88.13 per barrel. WTI is anticipated to average $82.98 per barrel. Analysts predict prices will moderate during the first quarter of next year, with Brent declining to $83.44 and WTI to $79.88.
China’s crude consumption patterns remain challenging to forecast. The nation has drawn down strategic reserves accumulated prior to the conflict, reducing its immediate purchasing requirements. Goldman Sachs reports Chinese crude imports increased 6% in September versus August levels.
Concurrently, U.S. refined product markets are experiencing tightening conditions. Gasoline inventories decreased 1.7 million barrels during the previous week. Distillate reserves, encompassing diesel and heating oil, fell 2.3 million barrels.
U.S. diesel prices achieved a record $6.53 per gallon last week. Diesel stockpiles remain at historically depleted levels. President Trump indicated Wednesday that deliberations continue regarding a potential prohibition on U.S. diesel exports. The White House previously refuted reports of a proposed 90-day comprehensive ban.
Russia is anticipated to prolong its diesel export limitations for an additional month. This measure compounds pressure on already constrained global fuel availability as the year’s final quarter approaches.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants



