


TLDR
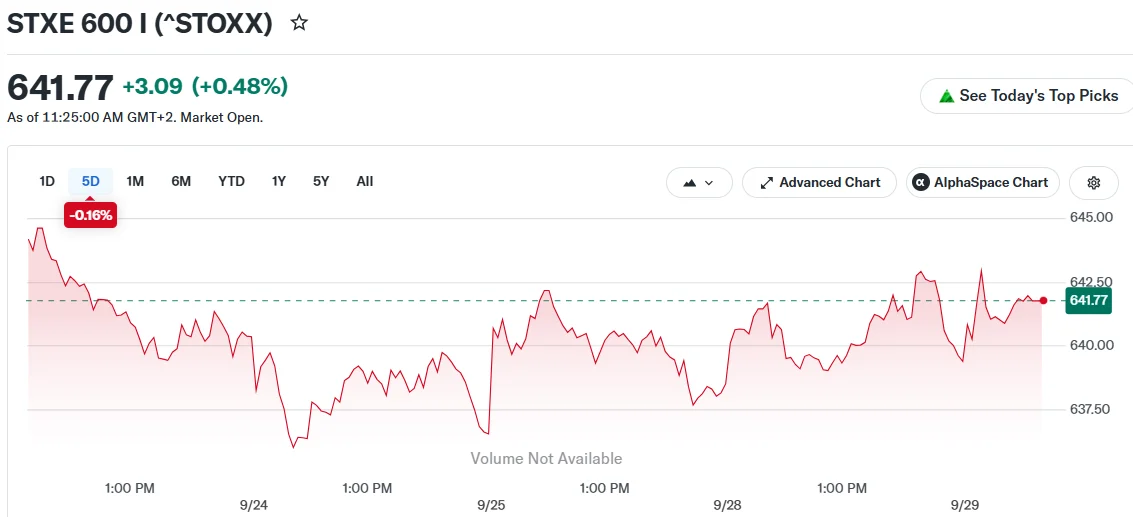
- Technology stocks drove European markets higher on Tuesday, with the STOXX 600 climbing 0.3%.
- Chip manufacturers rallied following reports that Anthropic is preparing for a public offering potentially valuing the AI firm above $2 trillion.
- Energy markets remained tense as U.S.-Iran diplomatic efforts failed to ease price pressures.
- Swiss chocolate producer Lindt experienced a nearly 7% decline after reducing its 2026 revenue outlook for the second occasion this year.
- Julius Baer and Legrand emerged as session leaders following favorable corporate developments.
European stock markets traded in positive territory on Tuesday, with technology shares providing the primary momentum for the session’s advances.
The broad-based STOXX 600 index climbed approximately 0.3% to reach 640.28 points during morning trading hours. The majority of regional benchmarks similarly posted positive movements throughout the day.
The technology sector climbed to its strongest position in four weeks. The rally materialized following a Reuters exclusive regarding Anthropic’s intentions to pursue a public market debut.
According to the report, the artificial intelligence company’s offering could achieve a valuation exceeding $2 trillion. Market participants interpreted this development as evidence of renewed enthusiasm for AI-focused initial public offerings.
Technology Sector Drives Market Performance
Chip manufacturing stocks experienced notable appreciation in response to the Anthropic disclosure. City Index’s senior market strategist Fiona Cincotta noted that the news rekindled optimism surrounding the IPO pipeline.

This investment theme had faced headwinds in preceding weeks. Earlier in the month, executives from multiple artificial intelligence firms had advocated for more cautious expansion timelines, citing potential technology misuse concerns.
Those previous statements had dampened sentiment toward technology equities. Increasing government bond yields had simultaneously applied additional downward pressure.
Crude oil quotations maintained elevated levels throughout Tuesday’s session. Brent crude futures traded around $106.99 per barrel.
Prices remained buoyant as diplomatic negotiations between Washington and Tehran failed to produce substantive progress. Given Europe’s substantial reliance on fuel imports, escalating energy costs typically exert disproportionate pressure on the continent’s economies.
Government bond yields across major markets hovered near levels not witnessed in several decades. Investors continue grappling with inflation concerns connected to energy market dynamics.
Christine Lagarde, President of the European Central Bank, delivered remarks on Monday addressing current economic conditions. She indicated that this year’s inflationary acceleration has not yet triggered significant secondary effects throughout the eurozone.
Lagarde’s commentary implied that a gradual policy stance remains appropriate. The central bank had previously implemented a rate increase earlier in the month.
Notable Corporate Performance
Lindt emerged as the STOXX 600’s most significant decliner. The company’s shares dropped approximately 7%.
The Swiss confectionery manufacturer reduced its 2026 sales projection for the second instance within the current year. Management attributed the revision to softening consumer expenditure, heightened price consciousness among shoppers, and diminished demand associated with an extended European heatwave.
Competitors Barry Callebaut and Nestle also experienced declines following the announcement. Julius Baer demonstrated contrasting momentum, securing the position as the session’s strongest performer.
The Swiss financial institution’s shares surged nearly 8%. Switzerland’s financial market supervisor FINMA concluded enforcement actions related to private debt lending activities and client connections involving two politically connected Russian nationals.
Legrand similarly delivered impressive results. The French electrical equipment and digital building infrastructure provider’s shares advanced more than 7% after management elevated medium-term performance targets.
Across other European markets, London’s benchmark index appreciated roughly half a percentage point, supported by healthcare and mining sector strength. German and French indices registered more modest advances.
Spain’s year-over-year inflation metric accelerated to 4.9% in September. The nation’s retail sales contracted 0.4% on an annual comparison basis.
Sweden’s household confidence indicator improved to 102.2 in September. The country’s business sentiment gauge extended its winning streak to six consecutive months, advancing to 109.3.
Within fixed income markets, the U.S. 10-year treasury yield declined modestly to 5.23%. The UK equivalent rose to 5.39%, while Germany’s 10-year yield retreated to 3.62%.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants



