


Key Takeaways
- The greenback retreated modestly on Wednesday but remained near recent multi-week peaks before the Federal Reserve’s policy announcement.
- A 92% probability is assigned by markets to a 25 basis point rate increase, bringing the target range to 3.75%-4.00%.
- Guidance from Fed Chair Kevin Warsh during the subsequent press conference will be critical, particularly signals about whether this represents an isolated move or the beginning of a sustained tightening campaign.
- The yen gained ground with markets assigning an 80% likelihood to a Bank of Japan rate increase on Friday.
- Crude oil trading above $113 per barrel—driven by Saudi infrastructure attacks and Red Sea shipping disruptions—is intensifying inflation pressures that justify the tightening stance.
The U.S. dollar retreated modestly on Wednesday, breaking a six-session winning streak and stepping back from near multi-week peaks as foreign exchange traders adopted a cautious stance before the Federal Reserve’s anticipated interest rate announcement.
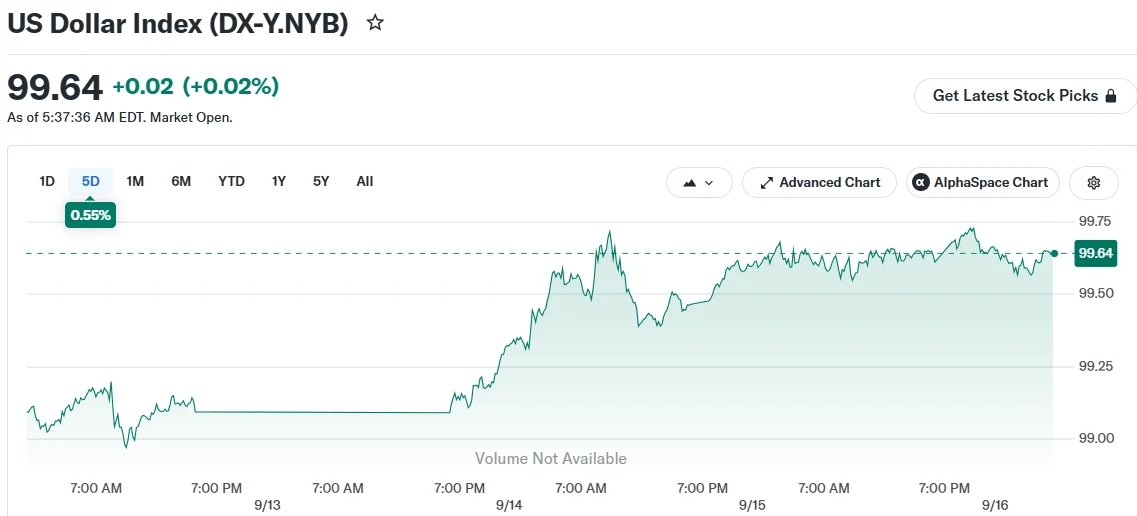
The Dollar Index, measuring the currency’s strength against a basket of six major counterparts, traded roughly unchanged around 99.59 following multiple consecutive sessions of appreciation.
Market pricing indicates a 92% likelihood that the Federal Reserve will implement a 25 basis point increase to its policy rate, establishing a new target range of 3.75%-4.00%. This would represent the first upward rate adjustment in the United States since the middle of 2023.
While the rate increase itself is largely anticipated, market participants are focused intently on the post-decision commentary from Fed Chair Kevin Warsh.
Traders are seeking clarity on whether Warsh will characterize this action as a standalone measure addressing elevated energy costs, or indicate the commencement of a sustained sequence of rate increases.

A more accommodative message could trigger dollar weakness as market participants secure gains. Conversely, hawkish rhetoric suggesting additional increases would likely support further dollar appreciation.
Elevated Energy Costs Fueling Inflationary Pressures
Crude oil prices have surged beyond $113 per barrel in response to strikes targeting Saudi Arabian pipeline facilities and Houthi military actions affecting Red Sea shipping lanes. These supply-side disruptions have elevated energy costs and amplified inflation concerns, providing justification for monetary policy tightening across global central banks.
ANZ strategists communicated to their clients an expectation for the Fed to implement rate increases at consecutive policy meetings, while acknowledging that the October gathering occurs in proximity to U.S. midterm elections.
The euro remained steady near $1.1554, trading not far from its one-month nadir. The European Central Bank implemented a 25 basis point increase to its deposit rate last Thursday, reaching 2.50%, similarly addressing energy-linked inflation pressures.
The British pound maintained levels around $1.3483. United Kingdom inflation accelerated to 3.1% in August from July’s 2.9%, while core inflation remained unchanged at 2.6%. The Bank of England will announce its policy decision on Thursday. Market participants assign a roughly one-third probability to a 25-basis-point increase.
Japanese Yen Firms as BOJ Decision Approaches
The Japanese yen rebounded after touching a one-week trough of 155.49 against the dollar during early trading. The currency recovered to approximately 154.97 yen per dollar by midday sessions.
Market expectations assign an 80% probability to the Bank of Japan implementing a 25 basis point rate increase to 1.25% at Friday’s policy meeting. Pricing suggests two total rate increases by the conclusion of January.
The yen has received support from evolving hawkish sentiment regarding Bank of Japan policy, coordinated currency market intervention between the U.S. and Japan, and repatriation flows from Japanese institutional investors.
Julius Baer economist David Meier noted that the yen’s trajectory will remain substantially dependent on interest rate differentials across major economies and adjusted the firm’s USD/JPY projection to 155.
China’s yuan remained stable near 6.71 per dollar notwithstanding an expanding differential between Chinese bond yields and rates prevailing in other major developed markets.
Market attention remains concentrated on Warsh’s press conference as the most significant driver for the dollar’s subsequent direction.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants



