Key Takeaways
- Cantor Fitzgerald analyst C.J. Muse reaffirmed his $2,000 price target for Micron shares following October’s decline.
- The price objective implies roughly 119% potential appreciation from Wednesday’s premarket indication of $913.20.
- Strategic customer contracts could eventually account for approximately 50% of Micron’s total revenue.
- Tight memory supply conditions are projected to persist until 2028, underpinning bullish projections.
- Micron’s approximately $35 billion buyback program may accelerate repurchases beginning December 9.
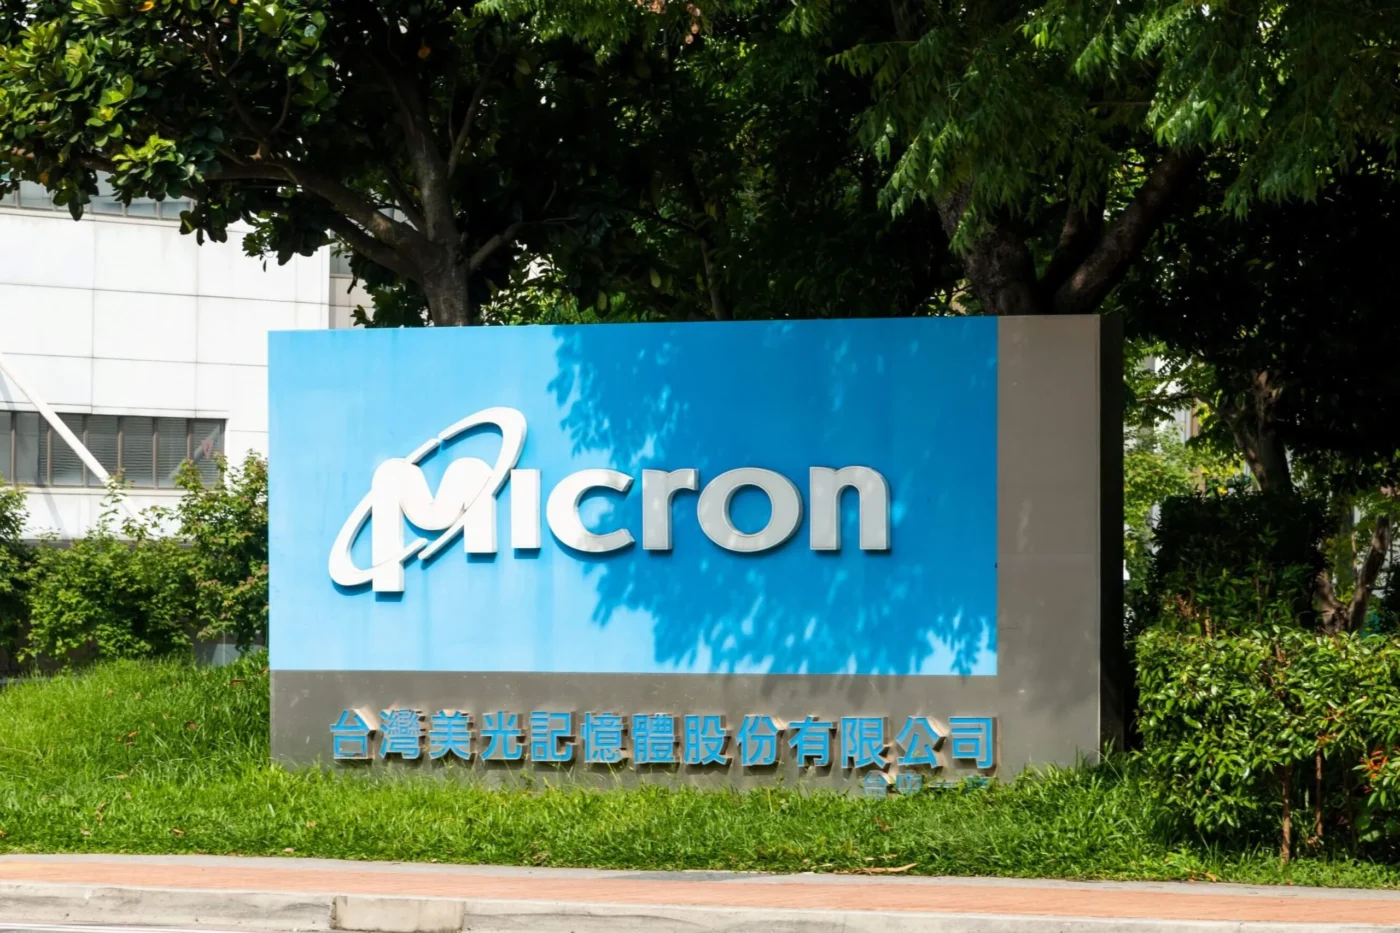
Micron (MU) shares have experienced significant weakness throughout October, yet one Wall Street analyst maintains conviction that the stock will more than double over the coming year. The memory chipmaker has dropped more than 17% this month as investors grapple with competitive dynamics and questions surrounding artificial intelligence infrastructure investments.
Cantor Fitzgerald’s C.J. Muse reiterated his Overweight rating alongside a $2,000 price objective on October 20. His assessment followed recent management commentary regarding long-term customer partnerships and industry supply dynamics.
Based on Wednesday’s premarket indication of $913.20, Muse’s target implies approximately 119% upside potential. This figure represents an analyst estimate rather than a guaranteed outcome.
Long-Term Contracts Strengthen Revenue Visibility
Muse highlighted 16 strategic partnerships Micron has secured, with 14 incorporating specific pricing structures. Management indicated these agreements may ultimately represent half of the company’s revenue stream, rising from 25% in May and 35% in August.

According to Muse, Micron has executed additional contracts at elevated price points. Meanwhile, an Intel stock rebound earlier this week demonstrated renewed investor appetite for semiconductor equities following a challenging month for technology names.
Micron anticipates memory supply will become tighter in 2027 compared to 2026, with constraints extending into 2028. Low customer inventory levels mean limited buffer against potential supply chain disruptions.
The semiconductor manufacturer produces memory components for data centers, mobile devices, and personal computers. Artificial intelligence workloads demand substantial quantities of high-bandwidth memory, driving increased demand for Micron’s offerings.
Semiconductor Sector Faces Broader Headwinds
A recent CoreWeave stock reversal illustrated broader challenges facing AI infrastructure providers. The cloud computing firm bounced back from early session weakness as market participants assessed its leverage profile and capital equipment requirements.
Micron’s October weakness coincided with pressure throughout the technology sector. Market participants raised questions about rising interest rates, substantial AI infrastructure capital expenditures, and potential competitive threats from Chinese memory producers.
Despite October’s pullback, Micron shares have surged nearly 343% over the trailing twelve months. The company’s market capitalization remained near $1 trillion despite recent declines.
TipRanks consensus data reflects 29 analysts with a mean twelve-month price target of $1,585.93 for Micron. That figure suggests approximately 74% upside from the referenced Wednesday premarket level, moderating below Cantor’s projection.
Muse anticipates Micron will increase share repurchase activity following December 9 utilizing its roughly $35 billion authorization. Recent AI chip market research similarly identifies memory availability as a production bottleneck.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants