


Key Highlights
- The Nasdaq Composite achieved a new all-time high, pushing futures upward across major benchmarks Tuesday morning.
- Shares of Nvidia advanced following robust earnings from Foxconn, indicating sustained appetite for artificial intelligence hardware.
- The 10-year Treasury note reached a closing yield of 5.31%, marking its highest finish in nearly a quarter-century.
- Technology companies with AI exposure, such as SpaceX, Tesla, Meta, and Microsoft, recorded notable advances in Monday trading.
- Crude oil declined Monday before recovering slightly Tuesday, with Federal Reserve meeting minutes scheduled for Wednesday release.
US stock futures advanced in early Tuesday trading as market participants continued to monitor corporate earnings and the persistent momentum in artificial intelligence capital expenditure. The upward movement occurred despite increasing government bond yields and higher diesel costs.
Nasdaq-100 futures climbed 0.1% following Monday’s record close for the Nasdaq Composite. Technology sector strength, particularly in Nvidia and related firms, contributed to the benchmark’s performance.
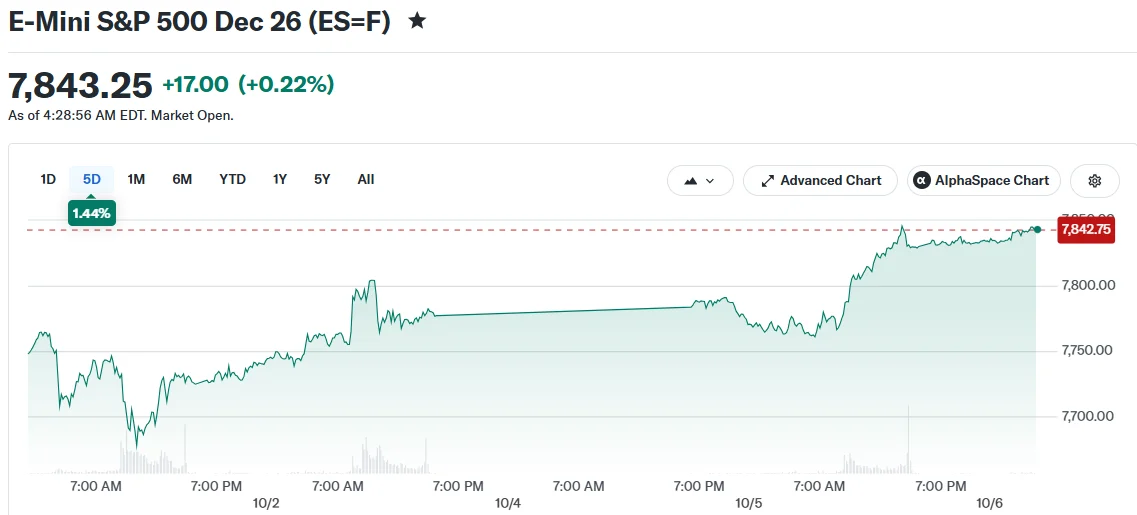
Futures tied to the Dow Jones Industrial Average added 0.1%, while S&P 500 futures edged into positive territory. The S&P 500 currently trades within 1% of its all-time peak.
Government Bond Yields Climb to Decades-Long Peaks
Fixed-income markets continued to command significant attention from investors throughout the week. The benchmark 10-year Treasury note finished at a yield of 5.31%, representing its strongest close in 24 years.
The 30-year Treasury bond yield advanced to 5.66%, a threshold last crossed in 2002. The upward pressure on yields has prompted wariness among certain market participants, despite ongoing equity strength.

In a client communication, Lisa Shalett of Morgan Stanley Wealth Management analyzed the recent bond market turbulence. She identified potential shifts in Federal Reserve policy direction, robust economic expansion, and elevated petroleum prices as key drivers.
Shalett also highlighted geopolitical tensions in the Middle East as a persistent risk factor. However, she emphasized that present volatility levels remain well below the intense swings witnessed during the 2022 equity downturn.
Technology Sector Powers Monday Rally
Equities tied to artificial intelligence applications delivered strong performance during Monday’s regular trading hours. SpaceX surged more than 7%, while both Nvidia and Tesla posted increases exceeding 2%.
Meta Platforms and Microsoft each registered gains above 1%. The sector-wide strength followed an impressive earnings release from Foxconn, a critical Nvidia manufacturing partner based in Taiwan.
The Foxconn financial results underscored persistent worldwide appetite for AI computing infrastructure. Nvidia’s total market value now stands just below the $6 trillion threshold.
The Nasdaq Composite advanced approximately 1% during Monday’s session to establish a fresh record. The Dow Jones Industrial Average climbed roughly 90 points, representing a 0.2% gain. The S&P 500 added 0.7%.
Asian markets delivered mixed results in Tuesday trading. Japan’s Nikkei 225 increased 0.29%. South Korea’s Kospi slipped 0.23%, while Australia’s S&P/ASX 200 climbed 0.53%.
Hong Kong’s Hang Seng Index jumped 0.95%. Mainland Chinese exchanges remained shuttered for the Golden Week observance.
Oil prices retreated on Monday. Brent crude declined 1.9% to settle at $100.32 per barrel.
West Texas Intermediate crude fell approximately 1.8% to finish at $89.43 per barrel. Both benchmarks showed modest strength in Tuesday trading.
Corporate earnings reports are expected Tuesday from Constellation Brands and Lamb Weston Holdings. The broader macroeconomic data calendar features limited releases for the day.
Market observers are anticipating Wednesday’s publication of minutes from the Federal Reserve’s September policy meeting. The document may provide additional insight into the central bank’s latest deliberations regarding monetary policy and interest rate trajectory.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants



