


Key Takeaways
- Stock index futures showed minimal movement in early Wednesday trading.
- Markets await the August PCE inflation data scheduled for release at 8:30 a.m. ET.
- The 10-year Treasury yield surged to fresh multidecade peaks around 5.21%.
- ADP’s September employment report revealed 90,000 private payrolls added, surpassing expectations.
- Market pricing now shows roughly 50% probability of a Federal Reserve rate increase in October.
Equity futures displayed limited action during Wednesday’s pre-market session as market participants positioned themselves ahead of crucial inflation data.
Futures contracts tied to the Dow Jones and S&P 500 hovered marginally above unchanged levels. The Nasdaq 100 futures contract dipped roughly 0.1% following Tuesday’s negative session.
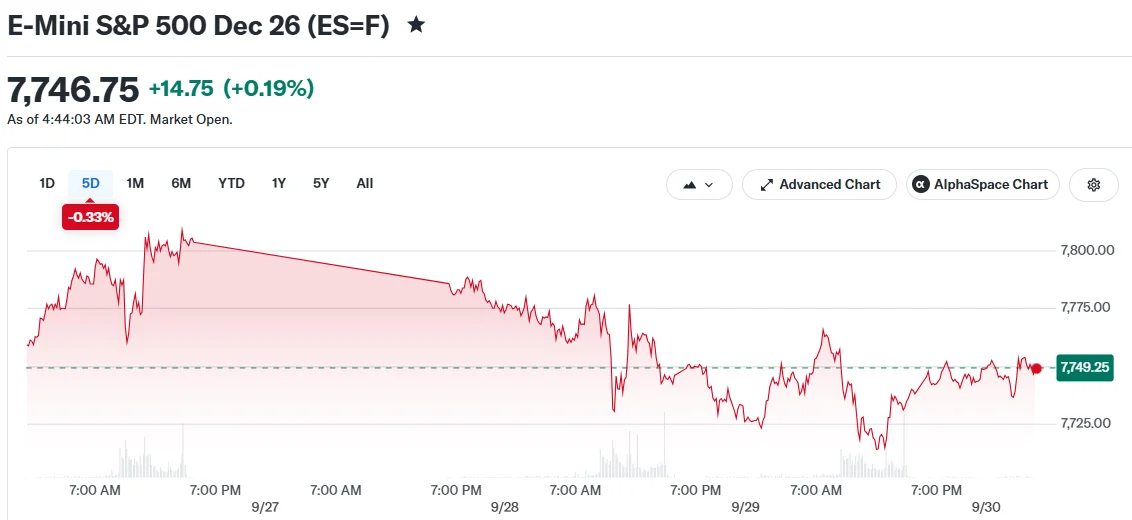
Bond market yields continued their ascent. The benchmark 10-year Treasury note reached price levels unseen in multiple decades, hovering around 5.21%.
PCE data takes center stage
Wednesday morning’s primary market catalyst is the Personal Consumption Expenditures price index for August. This metric represents the Federal Reserve’s favored inflation measurement tool.
Analyst consensus calls for the core measure, which strips out volatile food and energy components, to remain unchanged at 3.3% on an annual basis. This would represent no change from the previous month’s reading.

An inflation figure above projections might force market participants to recalibrate Federal Reserve policy expectations. Conversely, a softer print could alleviate some tension building within fixed income markets.
Oil prices remained under scrutiny as well. West Texas Intermediate crude futures traded steadily in the mid-$90s per barrel as Middle Eastern tensions surrounding Iran entered their seventh month.
Elevated energy costs typically filter through to broader inflation measurements, explaining why market participants are monitoring petroleum markets with heightened attention.
Employment figures and monetary policy outlook
Prior to the inflation release, ADP published its proprietary employment report. The data indicated 90,000 private sector positions were created during September.
This figure exceeded Wall Street projections calling for 70,000 new jobs. The reading also represented a substantial acceleration from August’s downwardly revised 36,000 additions.
Robust employment expansion can occasionally encourage the Federal Reserve to maintain restrictive monetary policy for extended periods. Financial markets displayed muted reactions immediately following the data release.
The 2-year Treasury yield climbed to 4.9% in response to the employment figures. The 10-year note moved higher from session lows.
Market participants have recalibrated their Federal Reserve policy expectations for the upcoming October decision. Current pricing indicates approximately 50% likelihood of a rate increase, declining from above 70% probability just one day prior.
New York Fed President John Williams remarked that policymakers face no pressing urgency to implement rate increases at next month’s gathering. Financial markets interpreted these comments as signaling potential pause in the tightening cycle.
Corporate results scheduled
Several quarterly earnings releases are positioned to capture investor attention throughout Wednesday’s session. Conagra Brands plans to announce financial results during pre-market hours.
Micron Technology has scheduled its earnings announcement for after the closing bell. The semiconductor manufacturer’s results should provide insight into memory chip demand and artificial intelligence infrastructure trends.
These corporate reports have potential to inject volatility into afternoon trading, particularly within technology and consumer staples segments.
Meanwhile, futures markets continue their wait-and-see approach. The primary market-moving event arrives when the PCE inflation figures release at 8:30 a.m. Eastern Time.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants



