


Key Takeaways
- UBS analysts highlight that climbing U.S. bond yields are presenting increasing challenges for European equity markets, with impact differing significantly across sectors.
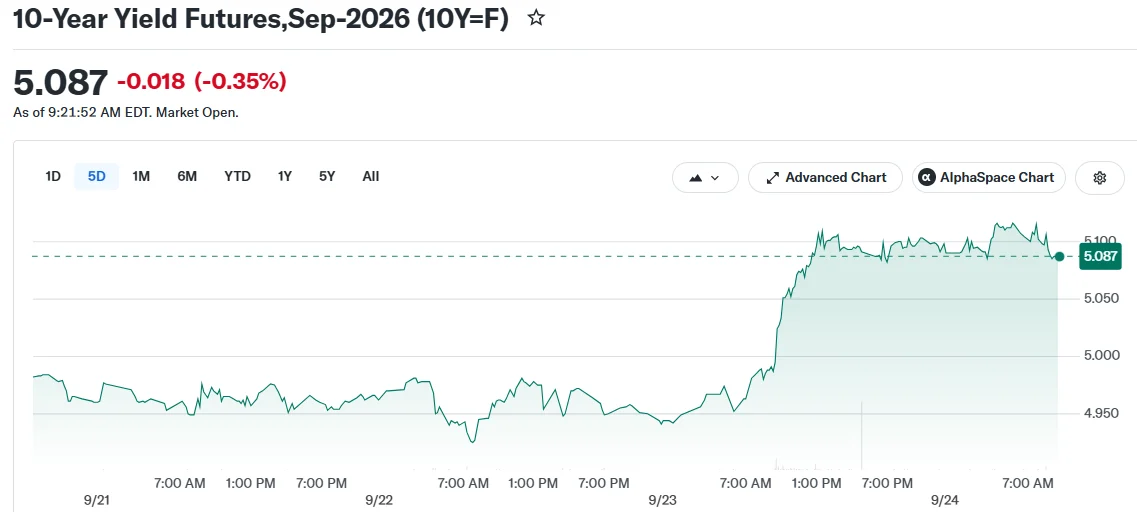
- The 10-year Treasury yield surged from 3.94% in February to reach 5.00% last week, while real yields jumped from 1.68% to 2.67% during the same timeframe.
- According to UBS strategists, the yield increase stems from expanding and strengthening economic growth rather than inflationary concerns, fueled by capital expenditure in defense, AI infrastructure, and power sectors.
- Over the past three months, energy, banking, chemicals and basic resources sectors have posted gains, while construction, telecommunications, utilities and food and beverage stocks have underperformed.
- European equity markets exhibited cautious trading on Thursday as market participants monitored escalating US-Iran tensions and anticipated a summit between Chinese and U.S. leaders.
European stocks are facing mounting pressure from rising bond yields, according to fresh analysis from UBS, which notes that the headwinds are affecting different market segments unevenly.
The U.S. 10-year Treasury yield has experienced a dramatic ascent since the beginning of the year. From 3.94% at the conclusion of February, it surged to 5.00% last week. Meanwhile, real yields—which account for inflation—jumped from 1.68% to 2.67% during the same stretch.
UBS strategists Gerry Fowler and Sutanya Chedda examined the performance patterns of the MSCI Europe index during periods of rising versus falling yields. Their analysis shows that since March 1, weeks characterized by rising yields saw only 42% of index components increase in value on average. Conversely, weeks with declining yields recorded 64% of components gaining ground.
This 22-percentage-point differential represents the most extreme divergence UBS has documented in their research sample.
The Relationship Between Yield Levels and Equity Performance
The analysts emphasize that absolute yield levels alone don’t tell the complete story. Rather, it’s the interplay between the level itself and the rate of change that determines market impact.

When the 10-year yield sits below 3%, even substantial weekly fluctuations left the majority of the index in positive territory. In this environment, rising yields were interpreted as signals of economic expansion.
Within the 4% to 4.5% territory, the dynamic shifts noticeably. Market breadth contracted from 61% during weeks of yield declines to merely 30% when yields surged by more than 20 basis points.
Beyond 4.5%, UBS notes that rapid weekly increases become particularly problematic for equity performance.
The Drivers Behind Climbing Yields
UBS contends that the yield surge isn’t rooted in concerns about inflation or turmoil in bond markets. Rather, the bank identifies an accumulation of industrial capacity investment spanning defense, AI equipment production, infrastructure development and power generation.
The firm characterizes this as the first coordinated capital expenditure cycle of this magnitude in a generation. This form of economic activity circulates capital through the economy more rapidly than services-oriented growth patterns.
UBS frames this development as a fundamental regime shift that markets haven’t had to account for in three decades. When money velocity accelerates against a steady monetary base, nominal GDP expansion quickens, and previously neutral monetary policy effectively becomes accommodative. This dynamic could necessitate additional interest rate increases rather than cuts.
The bank also cautioned that the consequences of policy adjustments may materialize more slowly than historical patterns suggest. Industrial investment operates on multi-year planning horizons. Capital already allocated to grid infrastructure, defense procurement and manufacturing facilities won’t be withdrawn in response to a single rate adjustment.
For market participants, UBS suggests prioritizing equities with minimal bond yield sensitivity, where earnings expansion can exceed the rising discount rate. During the past three months, energy, financial institutions, chemicals and basic resources sectors have advanced. Meanwhile, construction, consumer goods, telecommunications, utilities and food and beverage equities have retreated.
The strategists emphasize that the critical distinction isn’t simply between cyclical and defensive categories broadly. Instead, the determining factor is whether earnings growth proves sufficiently robust, and valuations adequately attractive, to counterbalance the drag from ascending yields.
During Thursday’s session, European stocks demonstrated tentative trading behavior. The STOXX 50 and STOXX 600 indices both oscillated near unchanged levels.
Market participants tracked evolving circumstances in the US-Iran confrontation, which maintained oil prices at elevated levels and kept bond yields hovering near multi-year peaks. Traders also looked ahead to a scheduled summit between Chinese and U.S. presidents for potential breakthroughs on trade disagreements.
Technology and banking sectors ranked among Thursday’s worst performers. SAP, UBS, Infineon, Mercedes-Benz and Rheinmetall all posted declines, while H&M shares tumbled nearly 3% following third-quarter earnings that fell short of analyst projections. LVMH, Novartis and Siemens recorded gains.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants



