


Key Highlights
- Treasury’s 10-year yield surged to 5.022%, marking the highest point in 17 years
- Futures for major indices including the S&P 500, Dow Jones, and Nasdaq all experienced early Tuesday losses
- Market anticipates a 25 basis point rate increase from the Federal Reserve on Wednesday
- Semiconductor stocks including Nvidia declined 3% while Corning plummeted 13% following industry calls for tempered AI expansion
- Crude oil markets saw gains, with Brent exceeding $107 per barrel
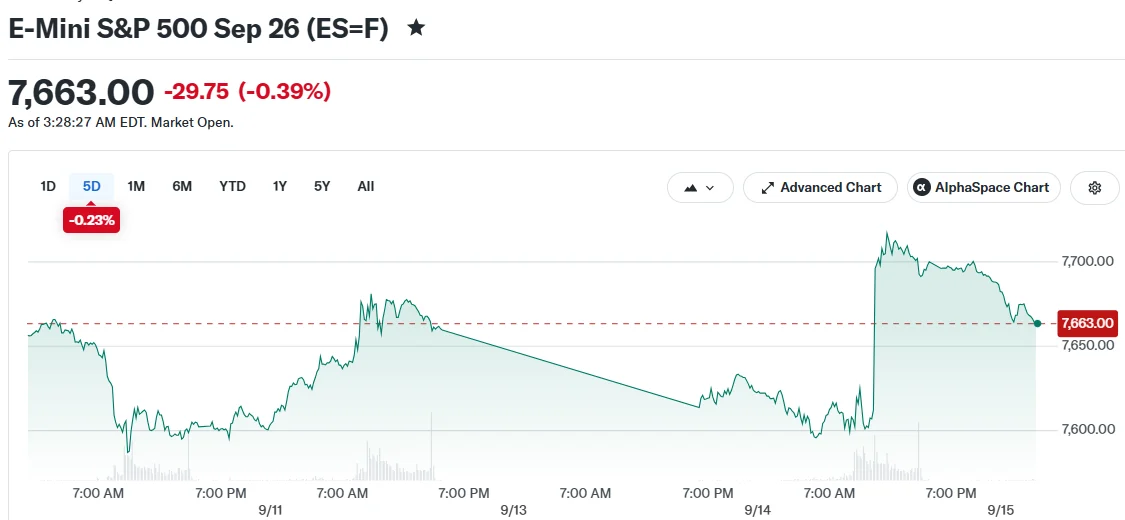
U.S. stock futures experienced declines during early Tuesday trading sessions as Treasury’s 10-year yield breached the 5% threshold for the first time in over sixteen years, creating downward momentum for equities while investors await the Federal Reserve’s upcoming policy announcement.
Futures tied to the S&P 500 decreased by 0.38%, while Dow Jones industrial average futures shed approximately 240 points, and Nasdaq 100 futures registered a 0.46% decline.
By early Tuesday trading hours, the 10-year Treasury yield had climbed to 5.022%, representing a 10 basis point increase. Treasury yields maintain an inverse relationship with bond prices.
During Monday’s standard trading session, the Dow Jones declined by 152 points, while the S&P 500 shed 0.5%, and the Nasdaq composite retreated 0.6%.
Federal Reserve Policy Decision Awaited
Market-based Fed funds futures indicate approximately a 92% probability that the central bank will implement a 25 basis point rate hike during Wednesday’s meeting. Such action would elevate the upper limit of the federal funds rate target range to 4%.

According to Christopher Hodge, who serves as chief economist at Natixis CIB Americas, the Federal Reserve is anticipated to signal that this rate adjustment doesn’t lock the committee into additional increases. He projects that Chairman Kevin Warsh will preserve the committee’s ability to respond dynamically to emerging economic conditions.
Rising interest rates present particular challenges for technology sector equities, whose valuations depend heavily on projected future earnings. As government bond yields climb, the present value of those anticipated earnings diminishes.
Analysts at Barclays emphasized that the 5% level on the 10-year Treasury yield represents a significant historical benchmark. They cautioned that continued yield increases could mean earnings expansion alone won’t sustain current equity valuation levels.
Semiconductor Sector Pressured by AI Development Concerns
Market sentiment weakened further following statements from prominent artificial intelligence industry leaders. During the weekend, Anthropic’s CEO Dario Amodei advocated for moderating the speed of AI advancement. Meanwhile, OpenAI’s CEO Sam Altman dismissed the possibility of a public offering this year, citing safety considerations.
The Philadelphia Semiconductor Index recorded losses exceeding 5% during Monday’s session. Nvidia’s shares retreated 3% while Corning experienced a sharp 13% drop. The iShares AI Innovation and Tech Active ETF declined nearly 4%.
Any deceleration in artificial intelligence development would translate to reduced expenditures on semiconductor components and data infrastructure, impacting revenue streams that have fueled the technology sector’s extended rally.
Software company shares moved in a positive direction, as concerns about AI-driven disruption in that segment eased with slower development expectations.
President Trump countered proposals for AI regulation and reportedly communicated with Nvidia CEO Jensen Huang to support continued data center expansion.
Energy market developments contributed additional market uncertainty. Brent crude climbed to $107.55 per barrel while West Texas Intermediate traded around $103.36 following Saudi Arabia’s pipeline closure. These supply disruptions heightened concerns about energy-related inflationary pressures.
Markets across the Asia-Pacific region showed mixed performance. Japan’s Nikkei 225 index remained unchanged, while South Korea’s Kospi decreased 0.74%, and Australia’s S&P/ASX 200 fell 0.8%.
Get 3 Free Stock Ebooks
Discover top-performing stocks in AI, Crypto, and Technology with expert analysis.
- Top 10 AI Stocks - Leading AI companies
- Top 10 Crypto Stocks - Blockchain leaders
- Top 10 Tech Stocks - Tech giants



